


N244 Applications to Set Aside a CCJ: Form, Evidence and Fees


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Form N244 is used to ask a court in England and Wales to make an order, including setting aside a County Court judgment. The right application depends on what happened in the case and what you need the court to do.
This guide covers the form, supporting evidence, fees and important limits of a set-aside application.
- What a Form N244 is used for.
- Good reasons to set aside a judgement.
- Where to send the N244 form.
- How to complete an N244 form online.
- How much an N244 application costs.
Dealing with debt can be quite scary, and unfortunately, it’s common to feel unsure about seeking help. In fact, Citizens Advice revealed that 60% of adults facing financial difficulties hesitate to seek assistance.1
If that’s your case, you’re not alone. We’re here to help you figure things out.
What is a Form N244 Used For?
N244 is an application notice used for a range of court orders. One use is asking to set aside a default judgment. It is not the normal form for responding to an initial money claim or simply disputing a debt before judgment.
An N244 application may also ask for a stay of enforcement, but submitting it does not automatically stop enforcement. Make any urgent request clearly and check whether the court has actually ordered a stay.
Download the current N244 form and official guidance, or ask the court for a copy.
N245 is commonly used to request instalments or a change to the rate of payment of a County Court judgment and to ask to suspend a County Court warrant. High Court enforcement and other applications can require a different procedure. Check which form fits your case.
What Should be Included along with N244?
In addition to the form itself, you need to include supporting documents for N244.
For a set-aside request, explain the relevant dates, how you learned about the judgment, any service problem, and the grounds on which you say the judgment should be set aside. Include documents that support the account.
A draft defence may help show the proposed defence, while a financial statement is relevant to an affordability application. Inability to pay alone does not establish grounds to set aside a default judgment.
Where Do I Send it?
Send the application to the court currently dealing with the claim, quoting its number. Check the latest order and court correspondence; if the case has been transferred, the original issuing centre may no longer be the correct destination.
Identify the parties who must be served and provide their service details. Follow the applicable rules and court directions about service rather than assuming that merely telling the claimant you have applied is sufficient.
If you don’t get a form from the court office, it is available online in PDF form from the government website, along with notes for guidance.
Can You Complete an N244 Form Online?
The PDF can be completed electronically, but that is different from filing the application online. Confirm the court’s accepted filing method and any email or document-size requirements. Keep evidence of filing.
Make multiple copies of the form, and your supporting documentation, so that you have enough to submit a copy to each party and to the court.
You should also make a copy for yourself.
» TAKE ACTION NOW: Fill out the short debt form
Do I have to attend court?
The court will decide whether a hearing is needed and how it will take place. Read the notice and attend as directed unless the court confirms a different arrangement.
A set-aside application may be sent to an appropriate hearing centre. The claimant can oppose the application and attend or be represented.
A set-aside hearing usually decides whether the judgment should be set aside, rather than finally deciding the whole disputed debt. The court may assess whether a proposed defence has a real prospect of success and give directions for the claim to continue.
If the claim continues, you must comply with the new deadlines and attend any later hearing. The order may also deal with costs.
HMCTS court staff can explain administrative processes but cannot act as your adviser or prepare a legal defence for you.
If the application is refused, the judgment normally remains in place. Consider the grounds and possible costs before applying, and act promptly if you need a set-aside.
How Much Does an N244 Application Cost?
The form is free to download. The civil court fee schedule, effective from 13 July 2026, gives £321 for a general application on notice and £126 for a general application by consent or without notice where no other fee is specified. The correct fee depends on the application; check before filing.
You may qualify for Help with Fees depending on savings, income, benefits and other eligibility rules. It is not restricted to people with no savings at all.
Use the Help with Fees service to check eligibility and apply.
Form EX160 is the paper application for Help with Fees; EX160A is guidance. Fee remission is separate from legal aid and does not itself provide a solicitor.
Steps to complete the form
Case Details
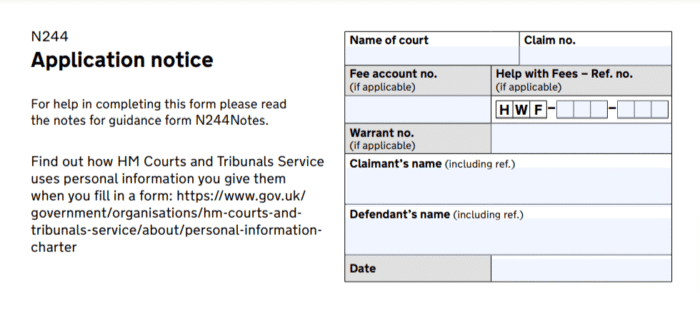
Use the current form and official notes. The following points address a defendant applying in an existing claim; they are not answers that fit every application.
Name of Court: Write the name of the court where the case was heard, or where it’ll take place.
Claim no: This can be found on court documents
Fee account number: complete only if you have an applicable fee account; otherwise leave it blank.
Help with Fees: Leave blank unless you’re applying for help with court fees.
Warrant no: If the claimant applied for a warrant of control, you will find the warrant number on an enforcement notice. If not, you can leave this box blank.
Claimant’s name: use the claimant’s name and reference from the court papers. The claimant may be an individual or an organisation.
Defendant’s name: Write your full name
Date: This is the date you filled this form out
Application Details
Question 1: Write your full name
Question 2: identify your role accurately. If you are the defendant applying for yourself, select Defendant. The legal-representative detail is for someone acting in that capacity.
Question 3: State the order you’re applying for and the reason why
Question 4 asks whether you have attached a draft of the order you want the court to make. It does not ask whether you received legal advice.
Question 5 asks how you want the application dealt with. The court decides whether a hearing is necessary. The official notes describe circumstances in which an application may be considered without a hearing:
- all the parties agree to the terms of the order being asked for
- all parties agree not to attend a hearing
- the court doesn’t think it’s appropriate
If you need a remote hearing or other adjustment, explain the request and check the court’s requirements. Do not assume your preferred format has been granted.
Question 6: Leave this blank if you don’t know
Question 7: Write ‘N/A’ unless you have been allocated a trial date or period
Question 8: Leave blank unless you know your case is being dealt with by a Master, District Judge or Judge
Question 9: identify who should be served with the application, normally including the claimant for a defendant’s set-aside application.
Question 9a: supply the required service address details for parties identified in question 9, following the form’s instructions.
Evidence
Question 10: Tick the relevant box.
Question 10 allows reliance on an attached witness statement, a statement of case, or evidence in the form’s box. Select the option or options that actually apply and attach the documents relied on.
Provide relevant, accurate evidence in a clear order. More paperwork does not automatically improve an application. Explain any delay and identify the documents supporting the grounds you rely on.
Statement of Truth
Read and complete the statement of truth honestly, then sign and give the required contact details. Also complete the question about vulnerability and any support or adjustments you or a witness need. See the official completion notes.
N244 Form CCJ Details
| Contact Details for Courts and Tribunals | https://www.gov.uk/find-court-tribunal |
| N244 Form | https://www.gov.uk/government/publications/form-n244-application-notice |
Good Reasons to Set Aside a Judgement
For a default judgment, Civil Procedure Rule 13 distinguishes cases where the court must set it aside from cases where it has discretion.
Examples of matters relevant to those rules include:
- Whether default judgment was wrongly entered because the required conditions were not met, or the claim had already been fully satisfied before judgment.
- Whether there is a real prospect of successfully defending the claim or another good reason to set aside the judgment or allow a defence.
- Whether the application was made promptly, where the court is exercising its discretion.
- What the evidence shows about service, the response deadline, the proposed defence and the reason for any failure to respond.
When a CCJ is set aside, it means that the judgement is, effectively, cancelled. As a result, it is removed from your credit history. However, that doesn’t mean that the debt suddenly disappears or that the court action is halted.
Setting aside a judgment removes that judgment, but the underlying claim may continue. Follow the order carefully: the claimant may still succeed later.
It is not a route to erase a valid debt solely because the judgment is inconvenient or unaffordable.
Court Hearings
A judgment after a missed hearing is not necessarily a default judgment under Part 12. Different rules can apply, including rules for non-attendance at a trial or small-claims hearing. Obtain advice about the correct application and deadline.
Explain promptly why you did not attend and what evidence supports your position. Do not assume that missing a hearing automatically creates a right to another one.
Court Papers
A default judgment may be entered where the conditions for judgment following a failure to acknowledge service or defend are met.
If the claim went to an old address or did not reach you, check the service rules and the evidence. Non-receipt alone does not automatically establish that service was invalid.
A court must set aside default judgment where Rule 13.2 applies. Otherwise it may consider Rule 13.3. An adviser can help identify the correct basis rather than treating every procedural complaint as sufficient.
Statute Barred
A limitation defence may support an application, but set-aside is not automatic merely because you describe the debt as old. You must address the applicable set-aside rules as well as the proposed defence.
Many simple-contract claims in England and Wales have a six-year limitation period, but other claims have different rules. The period runs from the relevant cause of action, not necessarily the loan date or credit-file default date.
Payments, valid written acknowledgment and earlier proceedings can affect the position. An existing CCJ does not disappear when the original debt or judgment reaches six years. Seek advice before relying on limitation.
When a CCJ is set aside, the court should arrange for the register to be updated. Keep the order and check your credit reports; a later judgment on the continuing claim could be registered separately.
References





