


NewDay Arrears: Letters, Payments and Your Options


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
If you have received a letter from NewDay about an unpaid balance, check which credit account it concerns and whether the information is correct.
NewDay is a consumer credit provider and servicer, not simply a collection agency hired by shops to recover unpaid purchases.
This article will provide simple and clear information on:
- Who NewDay is and which account the letter concerns.
- How to check a balance or dispute a mistake.
- How to respond to their letter.
- Ways to handle debt collectors.
- What happens if you ignore their letter.
We know that getting a debt collection letter can be worrying. It can be confusing to understand where the debt came from or if it’s real. You might be wondering how to pay if you can’t afford it. But there’s no need to panic; we have lots of helpful advice and examples to make things easier for you.
Let’s get started.
Why did I get a Letter?
NewDay provides and services credit accounts, including credit cards and retail finance. A letter may relate to arrears on a NewDay account or a brand it administers; it does not necessarily mean another retailer has hired a debt collector.
Check the brand, account number and balance against your statements. Use contact details in your verified app, account documents or NewDay’s official website rather than an unexpected payment link.
How do you respond?
If the account is unfamiliar, ask NewDay to explain it and investigate any genuine dispute. If it is yours but unaffordable, contact it promptly about support and affordable payments.
Bankruptcy and an IVA have substantial consequences and are not default responses to a collection letter. A free debt adviser can help assess your whole situation before you choose a formal solution.
» TAKE ACTION NOW: Fill out the short debt form
What is a Prove the Debt Letter?
Ask for the creditor’s name, account reference, balance breakdown and evidence that you are liable. For regulated consumer credit debts, a firm must pause recovery while it investigates a dispute on valid or potentially valid grounds. A request for information does not itself cancel the debt or extend a court deadline.
This is a great step to take if you believe that you were not the person who should be paying. Sometimes, errors do happen, so asking them to produce evidence that you are the one who owes the money allows for certainty about this on all sides.
Should I Pay?
If the debt is valid and enforceable, consider how to address it without missing essential costs or priority bills. Ask for support if you cannot maintain payments.
Ignoring genuine correspondence can leave errors unresolved and allow arrears to grow. Court action is possible in some cases, but is not inevitable.
You do not have to pay on an unexpected call. However, a Letter of Claim or court claim has a response deadline that must be dealt with separately.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
What Happens if I Ignore It?
NewDay may continue collection, arrange support, use a collection agent or take lawful legal steps. Which action follows depends on the account; NewDay is not simply paid a commission by retailers to chase every purchase.
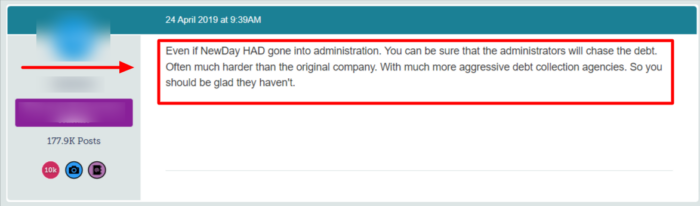
Image src: The Money Saving Expert Forum
There is no single automatic next step after a missed response. Read the actual notice and check its deadline.
Ask for information and suitable support. An informal conversation does not automatically pause all recovery or extend a court deadline.
You can request a suitable contact method and keep written records.
For many unsecured debts in England and Wales, the usual limitation period is six years from the relevant cause of action, not simply the last phone call. A payment, qualifying written acknowledgement or court proceedings can affect the position. Scotland usually has a five-year prescription period for many ordinary debts, with different rules and exceptions. Court judgments, secured debts and some tax debts require separate advice. Get free debt advice before paying or acknowledging an old debt; do not ignore court papers.
- Check when a legal right to claim arose, not just when the card or loan was opened.
- Check any payments made during the relevant period.
- Check qualifying written acknowledgements and whether proceedings were started in time.
- A court judgment has separate enforcement rules and does not simply expire when it leaves a credit file.
How Long Before a Debt is Unenforceable?
There is no universal age at which every debt disappears.
- A debt adviser can assess the account history and any judgment.
- If court papers arrive, get advice and respond within the deadline even if you think limitation applies.
Do not make a payment or admit liability on an old disputed account until you have checked the position.
Reviews
Online review scores change and reflect individual experiences. Check the date and product concerned; a rating cannot establish whether your own balance is correct.
If your problem concerns service or account accuracy, use NewDay’s complaints process and keep evidence.
A reviewer’s use of a credit limit is not a guarantee of a higher credit score. Borrow only what you can afford and follow your own agreement.
Why is it on my bank statement?
A NewDay entry can relate to a payment towards a credit card or finance account it provides or services. It is not necessarily a direct charge for a purchase from a particular retailer. Check the reference against your account and ask NewDay and your bank about any unfamiliar transaction.
Who owns NewDay?
NewDay’s ownership and funding structure has changed. Companies House currently lists KKR & Co. Inc as a person with significant control of NewDay Group UK Limited, notified on 18 February 2026.
- NewDay announced completion of KKR’s acquisition of its consumer credit receivables portfolio in October 2025.
- The operating and servicing arrangements should be checked against your account notices; a corporate transaction does not cancel an existing balance.
What do ownership changes mean for customers?
Check who provides and services your product on the agreement and subsequent notices. An investment-group name is not a reason to change payment details without independent verification.
Is Newday part of Amazon?
NewDay’s former Amazon card relationship is historical. NewDay is not part of Amazon, and an old card account should not be confused with Amazon’s current credit products.
Some former co-branded card customers moved to Pulse. Check the letters and current account details that apply to you; a transition announced for 2023 is not a future change.
What is Pulse?
Pulse is a NewDay credit card offered by invitation to selected existing customers. It is not a debit card. The invitation explains any transfer and the terms that apply.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Are they a UK company?
NewDay provides and services consumer credit in the UK. Use your agreement and current statements to identify the product and legal provider.
| Business | Consumer credit provision and servicing |
| Account to check | The specific brand and reference on your agreement or statement |
| General customer enquiries | 0333 220 2532 |
| Official details | NewDay contact page |
Are they the same as Aqua?
Aqua is a NewDay credit-card brand. Rates, limits and eligibility vary and can change; use the current official terms and your own agreement rather than an old headline APR.
What they consider to be high risk comes from your credit score and your past behaviour. Some of the things they might look at to assess this risk are not limited to the following:
- How many debts you have in total
- How recently you applied for another loan
- Your credit-file payment history and recent searches; rejected applications are not separately listed simply as rejections.
- How much you owe, relative to your earnings
- Whether you are a homeowner or have a mortgage
Are Marbles owned by them?
Marbles is a NewDay credit-card brand. Check its current official product information for rates, fees, limits and availability rather than relying on a historic range.
A soft-search eligibility check can indicate the likelihood of acceptance without the same footprint as a full application. It is not a guarantee.
A full application may involve a hard search and further affordability checks. Check the terms before applying.
If you are already struggling with repayments, free debt advice may be more appropriate than applying for another card.
Is Bip owned by them?
Bip is a NewDay digital credit brand. Check the current official product terms for availability and eligibility.
Bip is 100% digital and you do not receive a card. From your mobile, you operate within mutually agreed spending limits.
What credit cards are owned by them?
NewDay has operated a range of credit-card brands, including:
- Aqua
- Marbles
- Opus
- Fluid
- Pulse
NewDay also offers retail finance products. These are not all credit cards and do not all have the same terms; check the specific agreement and current retailer information.
The interest rates will likely increase the total amount you end up paying. Unless you are with a 0% interest period. This varies from card to card.
How do I make a complaint?
Use NewDay’s official contact page, your app or the contact details for your particular product. The general customer enquiry number is 0333 220 2532.
Opening hours can vary by product and change. Check the current official contact page.
Do not rely on an old number or opening-hours listing when a deadline is approaching.
If you require additional assistance in the complaints process, there are Debt charities you can approach who might be able to work with you on this.
If you feel like you are being harassed by NewDay Ltd in any way then citizens’ advice has information that might assist you.
To raise and escalate a complaint:
- Contact NewDay using its official contact details or the verified contact route for your product.
- To complain by phone, call 0333 220 2532
- If writing by post, use the current complaints address given for your product and keep a copy and proof of posting.
- An account message through the verified online account manager can also provide a written record.
- Complain to the firm first and keep copies and call logs. For an eligible regulated financial complaint, you can normally approach the Financial Ombudsman Service after a final response or after eight weeks without one, usually within six months of the final response. The Ombudsman can require a remedy or compensation; it does not impose regulatory fines. Tax, council and other non-credit debts may have different complaint routes.
- This complaint will need to be made within six months of the final decision letter from NewDay
- The Financial Ombudsman Service’s freephone number is 0800 023 4567.
- Use the Ombudsman’s official website for its current postal and online complaint options.
- Include the account details, what went wrong, relevant correspondence and the outcome you want.
- Check the Financial Ombudsman complaint guidance for eligibility and time limits.
Keep account payments and legal deadlines under review while a complaint is being considered; complaining does not automatically suspend them.





