


UKSL Debt Letters: Check UK Search Limited and Your Options


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Received a UKSL debt letter? UKSL is UK Search Limited, which collects accounts for clients. Verify the sender, creditor and balance before deciding what to do.
This guide explains how to check a demand and find independent support.
In this guide, we’ll:
- Help you understand who UKSL is and why they might be contacting you.
- Show you how to check if you really owe the debt.
- Give you advice on what to do if you can’t afford to pay.
- Talk about how dealing with UKSL might affect your credit score.
- Explain ways to get free debt advice.
Collection contact can be stressful. You can ask for communication that takes account of a health condition, disability or other support need.
This guide will give you the information you need to handle this situation with confidence. So, let’s get started.
Dealing with UKSL Debt – next steps
Start by checking the demand and keeping a record of your response.
Check your letters
Read the letter to identify the original creditor, current owner and UKSL’s role. Do not assume that a collection agency purchased your account.
Compare the balance with your records and request a breakdown of payments, interest and charges. An error does not automatically cancel the entire debt.
Prove the debt
Ask for the creditor’s name, account reference, balance breakdown and evidence that you are liable. For regulated consumer credit debts, a firm must pause recovery while it investigates a dispute on valid or potentially valid grounds. A request for information does not itself cancel the debt or extend a court deadline.
Follow our ‘prove it’ guide with letter templates and get them to prove that you owe the money.
Statute-barred debts
Many ordinary unsecured debts may become statute-barred after six years in England and Wales, or prescribed after five years in Scotland. The start date, debt type, payments, legally relevant acknowledgments and any court claim all matter. A creditor’s letter alone does not restart the period. Ask a debt adviser to check the facts before paying or admitting liability, and respond to any court papers on time.
Whether an older balance can be enforced depends on the debt and the applicable limitation or prescription rules.
In England and Wales, limitation can provide a court defence. Scottish prescription can extinguish an obligation. Obtain advice and respond promptly if proceedings arrive.
Keep in mind that not all debts become statute-barred!
Tax debts, judgments and mortgage debts can follow different rules. A CCJ does not expire when its credit-file entry disappears; later enforcement can face additional requirements.
Keeping a diary
Keep copies of letters and a dated record of calls, including what was discussed. This can support a dispute or complaint.
Put down the times and dates of all instances of contact they make, and if you can, note down the names of anyone you speak with.
If problems arise later on, you’ll have plenty of information to hand that will prove you had been active in your dealings with them.
If you negotiate a payment plan or they agree to write off some of the debt, we recommend getting this agreement in writing before you make your first payment. This will make it much more difficult for them to argue with you down the line.
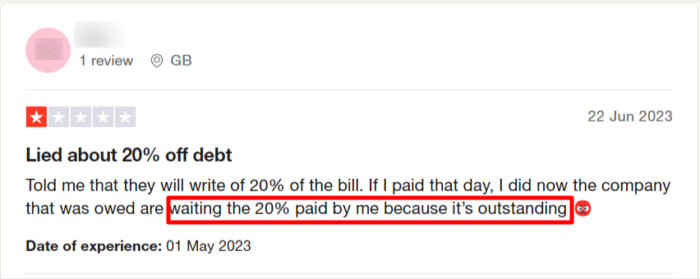
If you are in a similar position as this UKSL reviewer, we recommend speaking to a debt charity.
In future, get your amended agreements in writing!
» TAKE ACTION NOW: Fill out the short debt form
What If You Can’t Afford The Debt?
If the balance is valid but unaffordable, explain your circumstances and request sustainable payments after essential costs and priority bills. No particular repayment offer is guaranteed.
If you can’t afford to pay UKSL, you may benefit from a debt solution.
There are several debt solutions available in the UK, which means you can find the best solution for your finances. You can get free financial advice from a debt charity to help you make this decision.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Debt Management Plan (DMP)
A DMP is an informal debt solution that lets you pay off your debts via a single monthly payment.
Because it is informal, it is not legally binding so you are not tied into a DMP for a minimum number of payments.
Individual Voluntary Arrangement (IVA)
An IVA is a formal insolvency arrangement managed by an insolvency practitioner. Your proposal sets out payments, any assets involved and fees. Once approved, it binds the creditors and debts covered by it and restricts recovery action; it is not a blanket ban on necessary correspondence.
Many IVAs involve payments for five or six years, but the agreed term varies. Qualifying unpaid debt is normally released only on successful completion. An IVA affects your credit record, may involve assets or home equity, and can fail if its terms are not met.
IVA suitability depends on your debts, affordable contributions or available assets, fees and creditor approval. There is no universal rule that you must owe several thousand pounds to more than one creditor. Get independent debt advice and compare other options before agreeing to an IVA.
Trust Deed
IVAs are not available in Scotland. A Scottish money adviser can compare a protected trust deed, the Debt Arrangement Scheme, sequestration and informal arrangements; a trust deed is not compulsory.
A protected trust deed is a Scottish insolvency arrangement, usually lasting at least four years of contributions. It can discharge qualifying unpaid debt on successful completion, but fees apply and your home or other assets may be at risk. Covered creditors cannot pursue payment outside it, but can still send required documents.
Debt Relief Order (DRO)
In England and Wales, a DRO may suit an eligible non-homeowner with low surplus income, limited assets and qualifying debts within the £50,000 limit. Detailed income, asset, vehicle and residence rules apply. An approved debt adviser checks eligibility and submits the application to the Insolvency Service.
During the usual 12-month DRO period, recovery of listed qualifying debts is restricted and you generally do not pay those debts. Continue paying essential ongoing bills and excluded debts. A DRO does not prohibit every required creditor notice. Qualifying debts listed in a DRO are normally discharged at the end if the order remains in force.
Bankruptcy
If you have debts but no realistic possibility of ever paying them off, you may need to declare bankruptcy.
Bankruptcy has an unfair stigma attached to it as it may be your only way of getting a financial fresh start. That said, it is a serious financial situation that should not be taken lightly.
Sequestration
Sequestration is the Scottish version of bankruptcy.
Scotland’s Minimal Asset Process is a route into bankruptcy for people who meet its conditions. Its application fee has been removed. Ask an approved Scottish money adviser to compare it with the alternatives and explain the effects on assets, credit and income.
Will UKSL Affect Your Credit Score?
A collection letter does not automatically create a new adverse credit-file entry.
Missed payments or an existing default may already be recorded, depending on the account.
A sale or referral for collection should not restart the original default date or misleadingly duplicate the outstanding balance.
An entitled claimant may bring court proceedings. A CCJ is a court judgment, not something UKSL can issue itself.
A CCJ normally stays on the register and credit file for six years. Full payment within one month can allow removal; later payment usually marks it satisfied for the remaining period. Lenders apply their own criteria.
Typical Debt Collection Process
A collector may contact you about missed payments, subject to applicable rules. Court action, judgment and enforcement are separate stages, each with requirements and deadlines; a collection letter alone is not a CCJ.
Here’s a breakdown of the debt collection process so you can consider it and be cautious. Check out our specialized guide if you’d like to learn more about the debt collector timeline.
| Possible stage | What can happen | What to do |
|---|---|---|
| Missed payments | The creditor or collector may contact you, apply contractual charges or issue required notices. There is no single timetable for every debt. | Check the debt and contact the creditor early. Prioritise essential bills and seek free debt advice. |
| Collection activity | Letters, calls or a proposed visit may follow. A collection agent has no power to seize your belongings. | Ask for identification and evidence of the debt. You do not have to let a debt collector into your home. |
| Letter of claim | A creditor may send a formal pre-action letter before making a claim. | Follow the response deadline and get advice; do not ignore it. |
| Court claim | In England and Wales, a creditor may apply for a county court judgment. A judgment and later enforcement are separate stages. | Respond to the claim by the court deadline, whether admitting it, disputing it or asking for time to pay. Attend if the court requires a hearing. |
| Enforcement after judgment | Where legally permitted, a creditor may seek enforcement such as an attachment of earnings, charging order or warrant of control. | Get advice promptly about the specific notice, available objections and affordable payment options. |
How Can You Complain About UKSL?
An ordinary debt collector has no right to force entry or seize goods. A visit must comply with applicable contact and privacy rules; there is no blanket ban on every doorstep visit. FCA rules prohibit workplace visits without prior consent for regulated consumer-credit collection. A collector must protect your privacy and must not disclose a debt to an unrelated person without a lawful basis. Contact with someone you have authorised, such as a debt adviser, is different. Keep evidence of any improper disclosure and complain.
If they violate these rules, you can complain.
So, if you think that UKSL has been unreasonable or behaved inappropriately, you can make a complaint.
Make your first complaint to UKSL so that they have the chance to sort out the issue themselves. If you feel that they have not taken your complaint seriously enough or have not addressed your issue properly, you can escalate matters.
Complain to the business first. If the activity falls within the Financial Ombudsman Service’s remit, you can normally escalate after a final response or eight weeks without one, usually within six months of the final response. The Ombudsman can require redress, such as compensation or correcting records; it does not fine firms or remove their authorisation.
Thousands have already tackled their debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Will They Give Up Chasing?
A collection letter does not by itself prove that a debt is enforceable. Limitation and prescription rules depend on the debt, where you live, payments or acknowledgements and whether court action has already been taken. Get free debt advice before paying or admitting liability for an old debt, and never ignore court papers.
UKSL Contact Information
| Address: | Unit 4 Gander Lane Barlborough, Chesterfield Derbyshire, England, S43 4PZ |
| Phone: | 01246 488 924 |
| Email: | [email protected] |
So that’s a guide as to what to do if UKSL debt have contacted you. Below, we answer some of the more commonly-asked questions about UKSL debt, and debt collectors in general.
References





