


What can debt collectors do? UK rights and enforcement limits


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
In the UK, debt collectors have the right to chase you for the money you owe. If you’ve received a letter from a debt collector, you might be feeling concerned and unsure about what to do next.
This guide distinguishes ordinary debt collection from court and bailiff enforcement, and explains where to seek help.
This article will explain:
- The powers and restrictions that apply to the type of debt and activity.
- The process of debt collection.
- The impact of debt on your credit score.
- Your rights when dealing with debt collectors.
If a demand is worrying, verify the sender, check the account and get free debt advice before making an unaffordable promise.
Let’s get started!
What are Debt Collectors and Creditors Allowed to Do?
Remember, all debt collection agencies must respect UK debt recovery laws.
In short, there are creditors rights UK too. Here’s a table summarizing the key aspects.
| Debt collectors may | Limits and protections |
|---|---|
| Contact you to seek payment | For regulated consumer credit, contact must be at reasonable times and respect reasonable requests about when, where and how you are contacted. |
| Ask to discuss the debt at a home visit | A collector has no bailiff powers, cannot force entry or take goods, and should leave when asked. |
| Explain possible court action | They must not mislead you about their powers or threaten action they cannot lawfully take. |
| Discuss an affordable repayment or settlement | Get agreed terms in writing and obtain free advice if you dispute the debt or cannot afford payments. |
| A creditor may seek a separate court enforcement order | A CCJ alone does not give a collector access to your bank account. A third-party debt order requires a separate court process. |
| A creditor may assign a debt | Check who owns it and who is authorised to collect; do not disclose payment details to an unverified caller. |
| Make proportionate follow-up contact | Harassment is prohibited. Requests about contact must be considered; necessary legal notices may still be sent. |
They can Chase You Regarding Your Debts
They Can Show Up at Your Home
But they should let you know when they are coming which is good practice.
Ordinary collectors cannot force entry or seize goods. Workplace contact is not universally banned in every situation, but must comply with applicable privacy and conduct rules and must not be used to cause improper embarrassment.
» TAKE ACTION NOW: Fill out the short debt form
They Can Add Interest and/or Additional Charges on Your Debt
Buying a debt does not give the purchaser new rights to add charges merely because its purchase contract says so. Interest or fees need a lawful basis in the underlying agreement or other applicable law. See related guidance.
General household-debt statistics do not establish the interest owed on your account. Ask for an itemised balance and calculation.
For relevant regulated debts, the firm must apply the applicable forbearance rules and consider your circumstances. A request does not create a universal automatic interest freeze.
When can money be taken from an account?
Your Creditors can Apply for a Court Order or a County Court Judgement (CCJ)
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Your Creditors Can Issue a Default Notice
Checking for Other Debt Collectors
There are a lot of ways to get into debt. In fact, it’s not uncommon to owe money to several companies at once.
Perhaps you have a mortgage, a car loan, a couple credit cards and an item or two you bought on buy-now-pay-later schemes. It’s easy to lose track.
That’s why it’s important to regularly check your credit report and bank statements to make sure you haven’t missed anything.
A sold debt may appear under a new creditor name on your credit report, but not every debt or collector is reported to every credit reference agency.
Some of the debt collectors you’re most likely to come across are PRA Group, Lowell and Cabot Financial.
What are Debt Collectors UK and Creditors Not Allowed to Do?
They are Not Allowed to Harass You
There are UK debt recovery laws that debt collectors must follow.
Workplace contact must respect privacy and conduct rules
They Cannot Threaten You with Legal Powers That They Don’t Have
Whether conduct is a criminal offence depends on the facts and law. Keep the evidence and obtain advice about the appropriate complaint or reporting route.
They Cannot Breach Data Protection Laws
Interest and charges need a lawful and fair basis
They Cannot Lie to You
Complain first to the firm. The Financial Ombudsman can consider eligible financial complaints; the FCA can consider regulatory information but does not decide your individual redress.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
What Should I Do if a Debt Collector Violates FCA Guidelines?
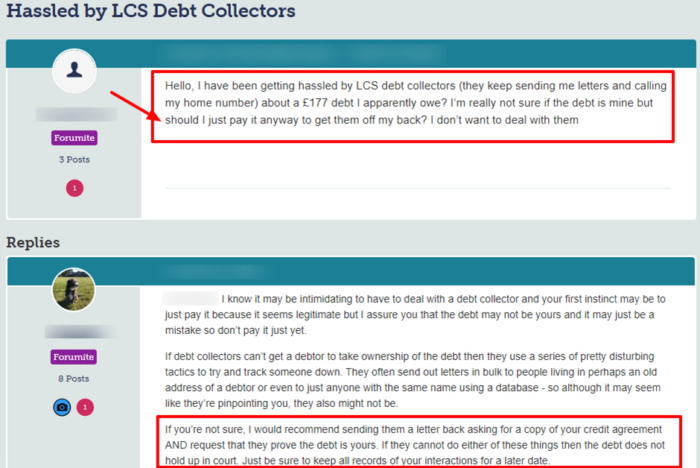
There are many debt collection agencies in the UK and not all of them behave according to the law.
See what one person posted on a popular forum and the reply that was posted.
Source: Moneysavingexpert
The impact of debt on your credit score
A CCJ normally stays on the register and credit file for six years from judgment. Paying the full judgment within one calendar month can allow the entry to be removed; paying later normally marks it satisfied rather than removing it. The debt does not automatically expire when the entry disappears.
Credit decisions depend on lenders’ policies and your circumstances. Removal of a CCJ record after six years does not itself extinguish the judgment debt.
Your Creditors can Issue a Statutory Demand
What if I can’t pay my debts?
If you owe a lot of money to several creditors and struggling to keep on top of payments, consider other debt solutions which I’ve listed below.
Debt Management Plan (DMP)
A DMP is an informal arrangement to repay eligible debts through an affordable payment. Creditors are not automatically bound to freeze interest or stop enforcement, and reduced contractual payments can affect credit records.
You can set a DMP up directly with creditors or you could opt to go through a leading UK charity or a debt management company.
Individual Voluntary Arrangement (IVA)
An IVA is a formal insolvency arrangement, subject to creditor approval and supervised by an insolvency practitioner. Fees, assets, included debts, term and failure consequences must be assessed.
You’d have to make the payment through an insolvency practitioner who then shares the money between the creditors you owe money to.
Administration Order
An Administration Order in England and Wales requires a qualifying County Court or High Court judgment, total debts not exceeding £5,000 and other eligibility conditions. A pending County Court claim alone is not sufficient.
You make monthly payments directly to the court which is then divided between creditors.
However, you must meet specific criteria to be eligible.
Debt Relief Order (DRO)
In England and Wales, a DRO may cover qualifying debts up to £50,000 where all income, asset and other criteria are met. Northern Ireland has its own process; DROs are not available in Scotland. See related guidance.
However, there are specific criteria attached to DROs which shouldn’t be overlooked.
Bankruptcy Order
Bankruptcy is one serious insolvency option, not automatically the only response to unaffordable debts. Compare alternatives with a free debt adviser.
In England and Wales, an individual’s own bankruptcy application is considered by an adjudicator. Scotland and Northern Ireland use different procedures.
Bankruptcy can put assets at risk. Discharge often occurs after one year in England and Wales, but asset realisation, excluded debts and some income-payment duties can continue beyond that date.
Consider the effects on your home, job, assets and credit record. Social attitudes do not alter the legal consequences.
As such, it’s a debt solution that needs careful consideration and expert advice should be sought first.
References





