


Can a Debt Collector Refuse a Payment Plan? Your Options


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you worried about a letter from a debt collector? You might be asking, “Can a debt collector refuse a payment plan in the UK?”
A collector can reject a particular offer, but regulated consumer credit firms must treat financial difficulty fairly and consider the customer’s circumstances.
In this article, we’ll help you find answers to questions like:
- Is the debt really yours?
- Can you ask the debt collector to stop bothering you?
- What are your choices for setting up a payment plan?
- Is it possible to get some of your debt written off?
This guide explains how to present an affordable offer and what to do if negotiation fails. A payment offer does not replace responding to court papers.
My Creditor Has Refused My Offer, What Should I Do?
Debt repayment negotiations are tricky! From my experience, having your offers rejected can be demoralising and quite stressful.
It might be an idea to do some more research on negotiating or even speak to a debt charity for some free and specific advice.
Explain Your Circumstances
» TAKE ACTION NOW: Fill out the short debt form
Check Before Making a Payment
Payments without an agreed arrangement do not by themselves bind the creditor to your proposal or stop interest or legal action.
Tell Them About Other Creditors that have Accepted Your Offer
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
My Creditor has Refused to Freeze Interest; What Should I Do?
You can also contact a debt charity for some free debt counselling or financial advice. Their advisers will be able to walk you through all of your options and help you develop a plan of action that is most likely to succeed. This could mean that you negotiate a different type of payment plan, you appoint a third-party mediator, or you opt for a formal debt solution.
I’ve Tried Everything and My Creditors Still Refuse to Accept My Offer, What Should I Do?
How Do I Complain About My Debt Collector?
If you think that your debt collector has been unreasonable or behaved inappropriately, you can make a complaint. You can also make a complaint if you feel that they have broken any of the Financial Conduct Authority’s (FCA) guidelines.
Make your first complaint to the debt collection company in question so that they have the chance to sort out the issue themselves. Most debt collection agencies have detailed and straightforward complaint procedures for you to follow on their website.
If you feel that they have not taken your complaint seriously enough or have not addressed your issue properly, you can escalate matters.
Complain to the firm first and keep copies and call logs. For an eligible regulated financial complaint, you can normally approach the Financial Ombudsman Service after a final response or after eight weeks without one, usually within six months of the final response. The Ombudsman can require a remedy or compensation; it does not impose regulatory fines. Tax, council and other non-credit debts may have different complaint routes.
Can I Get A Debt Solution?
If your creditors have refused your negotiations or offers and you are still struggling to pay your debts, you might need a debt solution.
There are several different debt solutions available in the UK. This means that you have options, and you can choose the debt management strategy that will be best for your finances. I recommend speaking to a debt charity before you begin a debt solution, as they can give you free advice and make sure that you are making the right decision!
Debt Management Plan (DMP)
A DMP is an informal debt solution that lets you pay off your debts via a single monthly payment.
Because it is informal, it is not legally binding so you are not tied into a DMP for a minimum number of payments.
Individual Voluntary Arrangement (IVA)
An IVA is an approved formal arrangement administered by an insolvency practitioner. It governs payments, fees and assets and binds creditors within its scope.
Many contribution-based IVAs run for five or six years, but the approved terms control. Only included debts remaining on successful completion are released; failure can leave you owing them.
There is no universal statutory minimum debt or two-creditor rule. Suitability depends on the proposed arrangement and your income, debts and assets, so compare alternatives first.
Trust Deed
IVAs are not available in Scotland. A protected trust deed is one possible Scottish option; a Debt Arrangement Scheme programme or bankruptcy may also be relevant.
A protected trust deed has its own rules, usually including four years of contributions and consideration of assets. It does not prohibit every creditor communication, and discharge depends on completion and the debts covered.
Debt Relief Order (DRO)
A DRO may suit someone within the applicable debt, asset and surplus-income limits. The criteria differ between England and Wales and Northern Ireland.
During the usual 12-month DRO period, recovery of listed qualifying debts is restricted and you generally do not pay those debts. Ongoing bills and excluded debts still need attention.
You must report relevant changes. Qualifying debts are normally discharged when the period ends if the order remains in force; not every unsecured debt is automatically included.
Bankruptcy
If you have debts but no realistic possibility of ever paying them off, you may need to declare bankruptcy.
Bankruptcy has an unfair stigma attached to it as it may be your only way of getting a financial fresh start. That said, it is a serious financial situation that should not be taken lightly.
Sequestration
Sequestration is Scottish bankruptcy. The Minimal Asset Process is a route for people who meet its conditions, and the application fee has been removed. Seek approved Scottish money advice.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
My Creditor is Threatening Me with Court Action, What Should I Do?
Staying On Top Of Your Debts
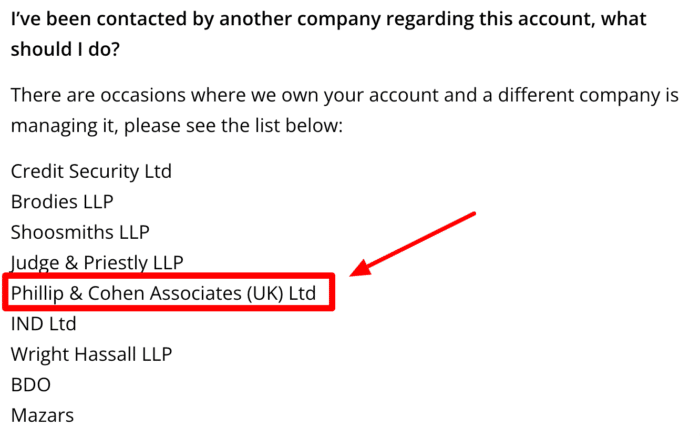
A letter may come from the original creditor, a debt purchaser or a separate collection agency. Check the business name and contact details against reliable records, and ask it to explain who owns the debt and its authority to collect. Keep earlier correspondence so you can trace any change of owner or representative.
- Robinson Way will sometimes contact you under the name Hoist Finance.
- Cabot Financial Group recently bought Wescot Credit Services
- Credit Style communicate as both Credit Style and CST Law.
- Lowell Financial also owns Overdales and collects debts under both names.
References




