


Capquest Debt Recovery: Letters, Disputes and Repayment Options


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Have you received a letter from CapQuest Debt Recovery out of the blue? Don’t worry, you’ve come to the right place.
This guide explains how to check the account and respond to collection or legal notices.
This guide will help you understand:
- How to make sure the debt is really yours, because if it’s not, you don’t have to pay!
- How you might stop CapQuest from contacting you too much.
- Your choices to set up ways to pay the debt, or even not pay some of it.
If the contact is worrying or payment is unaffordable, ask for support and free independent debt advice.
So, we’re here to help you learn more about how to deal with CapQuest Debt Recovery today.
Why Do Capquest Keep Calling Me?
An introductory collection letter, final demand, Letter of Claim and court claim are different documents.
Read the stated deadline and legal stage. A warning is not itself a judgment.
For regulated consumer credit collection, FCA rules require firms to give due regard to reasonable requests about when, where and how they contact you. You can ask for letters or emails instead of calls and explain any health or accessibility needs. This is not an automatic ban on every call or required notice. Keep a record of unreasonable contact and complain if your request is not properly considered.
Do not assume the demand proves liability or that an unfamiliar name makes it false. Check it independently.
Debt advice: Continue to the debt enquiry form
Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.
Send a Prove the Debt Letter
How the introduction works
The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.
Options depend on your circumstances. You decide whether to proceed.
Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
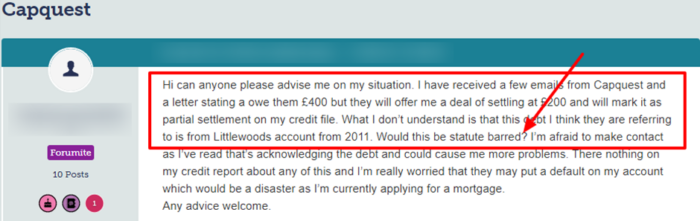
Is the debt statute barred?
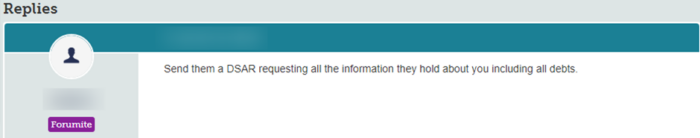
Check out this message a concerned person posted on a popular forum.
Source: Moneysavingexpert
Can Capquest Send Bailiffs?
A statutory demand is a different insolvency procedure. Get urgent advice if you receive one rather than treating it as an ordinary collection letter.
Debt Collectors vs Bailiffs
To make the previous section clearer, here’s a table briefly explaining the main differences between debt collectors and bailiffs, including what they can and can’t do.
| Issue | Debt collector | Bailiff or enforcement agent |
|---|---|---|
| Role | Requests payment for a creditor or debt purchaser. | Acts under a legally valid enforcement power and must follow its limits. |
| Entry | No power to force entry; you can refuse entry and ask them to leave. | Usually cannot force first entry to a home for council tax or an ordinary civil debt. Limited exceptions and re-entry rules apply. |
| Goods | Cannot seize your goods. | May take non-exempt goods belonging to the debtor where the legal conditions are met; essential items and some work equipment are protected. |
| Bank accounts | A judgment alone gives no access. | Taking money from an account normally requires a separate third-party debt order obtained by the creditor, not a doorstep bailiff power. |
| Contact | Must avoid harassment; regulated firms must contact at reasonable times. | Visits are normally between 6 am and 9 pm, subject to legal exceptions. |
| Vulnerability | Tell the firm what support or communication adjustments you need. | Tell the agent and creditor about vulnerability and seek advice about additional safeguards. |
| Disputes | Ask for evidence of the debt and complain about improper conduct. | Check identification, the enforcement authority and fees; get urgent advice about an invalid notice or proposed entry. |
An ordinary debt collector has no right to force entry or seize goods. A visit must comply with applicable contact and privacy rules; there is no blanket ban on every doorstep visit. FCA rules prohibit workplace visits without prior consent for regulated consumer-credit collection. A collector must protect your privacy and must not disclose a debt to an unrelated person without a lawful basis. Contact with someone you have authorised, such as a debt adviser, is different. Keep evidence of any improper disclosure and complain.
Will Debt Recovery Wipe My Debt?
During the usual 12-month DRO period, recovery of listed qualifying debts is restricted and you generally do not pay those debts. Continue paying essential ongoing bills and excluded debts. A DRO does not prohibit every required creditor notice.
That said, you could contact one of the charities to find out about setting up a Debt Management Plan (DMP).
Borrowing to consolidate debt can increase costs or put assets at risk. Compare independent debt advice and other options before taking new credit.
A budget can support a repayment or settlement offer, but there is no universal statutory requirement for a particular named assessment before making an offer.
About The Debt Advice Service
Use the enquiry form to request a call about your circumstances and available options. You decide whether to proceed.

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
CapQuest Debt Recovery Contact Details:
| Company | Capquest Debt Recovery Limited, company number 03772278; part of the Intrum group |
| Customer telephone | 0333 999 7200 |
| Correspondence address | Capella 60 York Street Glasgow G2 8JX |
| Online contact | Official contact page and account portal |
Where to Find Independent Debt Advice
Other debt charities include:
Citizens Advice
Checking for Other Debt Collectors
There are a lot of ways to get into debt. In fact, it’s not uncommon to owe money to several companies at once.
Perhaps you have a mortgage, a car loan, a couple credit cards and an item or two you bought on buy-now-pay-later schemes. It’s easy to lose track.
That’s why it’s important to regularly check your credit report and bank statements to make sure you haven’t missed anything.
A sold debt may appear under a new creditor name on your credit report, but not every debt or collector is reported to every credit reference agency.
Some of the debt collectors you’re most likely to come across are PRA Group, Lowell and Cabot Financial.
References





