


HO Collections on a Letter or Statement: How to Check the Claim


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
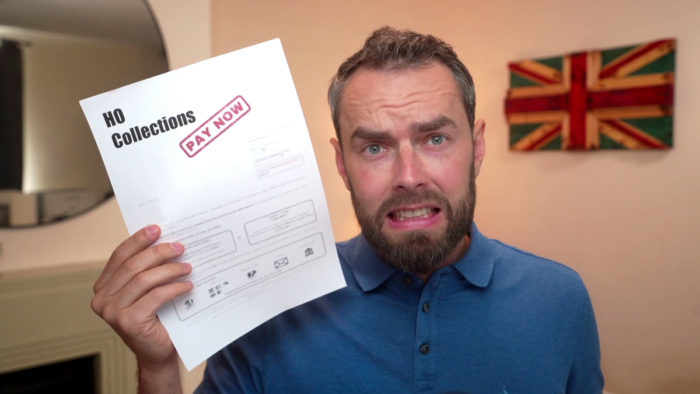
If a letter or bank statement refers to “HO Collections”, check who is behind it before paying or sharing personal information. The name alone is not enough to identify a creditor or collection agency.
This article will help you understand:
- How to identify the organisation contacting you.
- How to check whether a payment demand is genuine.
- Your possible choices to deal with this debt.
- How to request details of an alleged debt.
- How much debt is too much, and ways to legally write off your debt.
An unexpected demand can be worrying. Start with the original creditor or your bank, using contact details you have independently verified.
This guide explains how to check an unfamiliar collection reference and what to do if the debt is disputed or unaffordable.
The Truth About Your Debt
Ask the sender for its full legal name, the original creditor, the account reference and an itemised balance. Contact the original creditor through its official website or existing paperwork to confirm who is authorised to collect the account.
If you dispute the debt, explain the reason in writing and ask for supporting evidence. Keep copies and seek advice if court papers or enforcement notices arrive. Requesting evidence does not automatically cancel a debt or suspend a court deadline.
If the demand concerns a regulated consumer credit debt, FCA rules require a firm to investigate a dispute raised on valid or potentially valid grounds and suspend recovery while doing so. Different rules apply to other debts.
What options do I have?
A debt management plan normally repays eligible debts in full and does not guarantee a write-off. An IVA is a formal insolvency arrangement with fees, eligibility criteria and risks; it is not suitable for everyone.
If the debt is yours but unaffordable, prepare a budget and ask about an affordable payment arrangement. Prioritise essentials such as rent, council tax and energy, and get free debt advice before choosing a debt solution.
You can find free, impartial support through MoneyHelper’s debt advice locator.
» TAKE ACTION NOW: Fill out the short debt form
More Data
If the reference appears on your bank statement and you do not recognise it, contact your bank using the number on your card or its official app. Do not use an unverified number supplied in a message.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Checking for Other Debt Collectors
There are a lot of ways to get into debt. In fact, it’s not uncommon to owe money to several companies at once.
Perhaps you have a mortgage, a car loan, a couple credit cards and an item or two you bought on buy-now-pay-later schemes. It’s easy to lose track.
That’s why it’s important to regularly check your credit report and bank statements to make sure you haven’t missed anything.
A sold debt may appear under a new creditor name on your credit report, but not every debt or collector is reported to every credit reference agency.
Some of the debt collectors you’re most likely to come across are PRA Group, Lowell and Cabot Financial.
Check the company’s identity
We have not verified a UK debt collection firm from the name “HO Collections” alone. The website hocollection.com belongs to an Italian hospitality business. Its hotel contact details should not be used to enquire about a UK debt. Confirm the correct organisation with your original creditor or bank.
References





