


Judge & Priestley Debt Recovery: How to Respond


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Have you received a debt letter from Judge & Priestley? Its specialist debt recovery division is J&P Credit Solutions. Check the creditor, account details and deadline before deciding how to respond.
Every month, over 170,000 people come to our website for advice on debt matters. We understand how confusing and scary it can be to get a debt letter.
In this easy-to-understand article, we will tell you:
- How to find out if the debt is really yours.
- Why Judge and Priestley Debt Collectors may be contacting you.
- If you can ignore them or need to pay.
- How they might change the way they deal with you.
- Ways to stop them from bothering you too much.
Our team knows a lot about debt because some of us have had debt letters too. We understand how you feel, and we’re here to guide you.
Read on to find out more about Judge and Priestley Debt Collection and how to handle them.
Why you are being contacted?
Judge & Priestley LLP is a firm of solicitors. Its debt recovery division acts for clients in collection and litigation matters; a letter from it does not mean it has bought your debt.
Check whom the solicitors represent and whether the letter is an ordinary payment request, a letter before claim or a court document. The sender cannot issue its own court judgment, and the required response depends on the stage.
» TAKE ACTION NOW: Fill out the short debt form
Is this really your debt?
You could be wondering whether this debt is really yours. In which case, you should take steps to establish the origin of the debt, together with an understanding of the total costs of the debt. It is probably that the debt, if this does exist, is much higher than you remember, due to the various charges and interest. It could be so inflated that a seemingly small debt, has became quite large!
If you dispute the debt, explain why and ask for an itemised balance and evidence of liability. For recovery covered by FCA consumer-credit rules, a valid or potentially valid dispute must be investigated and recovery paused. A generic proof request does not cancel the debt, override an existing court order or extend a court deadline. Statutory consumer-credit information requests have separate requirements and do not apply to every debt.
Follow our ‘prove it’ guide with letter templates and get them to prove that you owe the money.
Should you pay?
As long as you have received confirmation that you owe the money, you should take steps to pay it back. If you can afford to, it is best to clear the debt, but if that is not possible, then set up a repayment plan. Judge And Priestley Debt Collectors should be willing to work with you, and your individual circumstances to develop an appropriate repayment structure.
Entering into an IVA
An IVA is a formal insolvency arrangement managed by an insolvency practitioner. The proposal sets out payments, assets, fees and the debts covered. Qualifying unpaid debts are normally released only on successful completion; an IVA affects your credit record, can put assets at risk and can fail if its terms are not met. Get independent advice and compare other options before agreeing.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
The legislation
The OFT closed in 2014. Solicitors are subject to professional regulation, and FCA rules may also apply to relevant consumer-credit activity. The standards applicable to the case include:
- They have a responsibility to ensure they treat debtors fairly. This includes refraining from using aggressive practice, or any unfair/improper behaviour.
- They must ensure transparency and clarity in all information they provide to borrowers. They must not attempt to mislead anyone.
- They are responsible for showing consideration to debtors, who may be in a difficult financial situation.
- They must take the debtors’ circumstances into account, before determining appropriate action.
Raise the complaint with the firm first. You can report serious professional misconduct by a solicitor to the Solicitors Regulation Authority, but it cannot decide the underlying debt dispute or stop a court case. The Legal Ombudsman generally deals with service complaints from eligible clients, not complaints about an opponent’s solicitor. Financial Ombudsman eligibility depends on the activity and complainant.
Use the firm’s current complaints procedure and keep copies of relevant evidence. A complaint does not automatically stop litigation or extend a court deadline.
Verify the sender using the firm’s official contact details, particularly if bank details have changed or you were contacted unexpectedly. The firm should make clear which creditor it represents.
Will They Give Up Chasing?
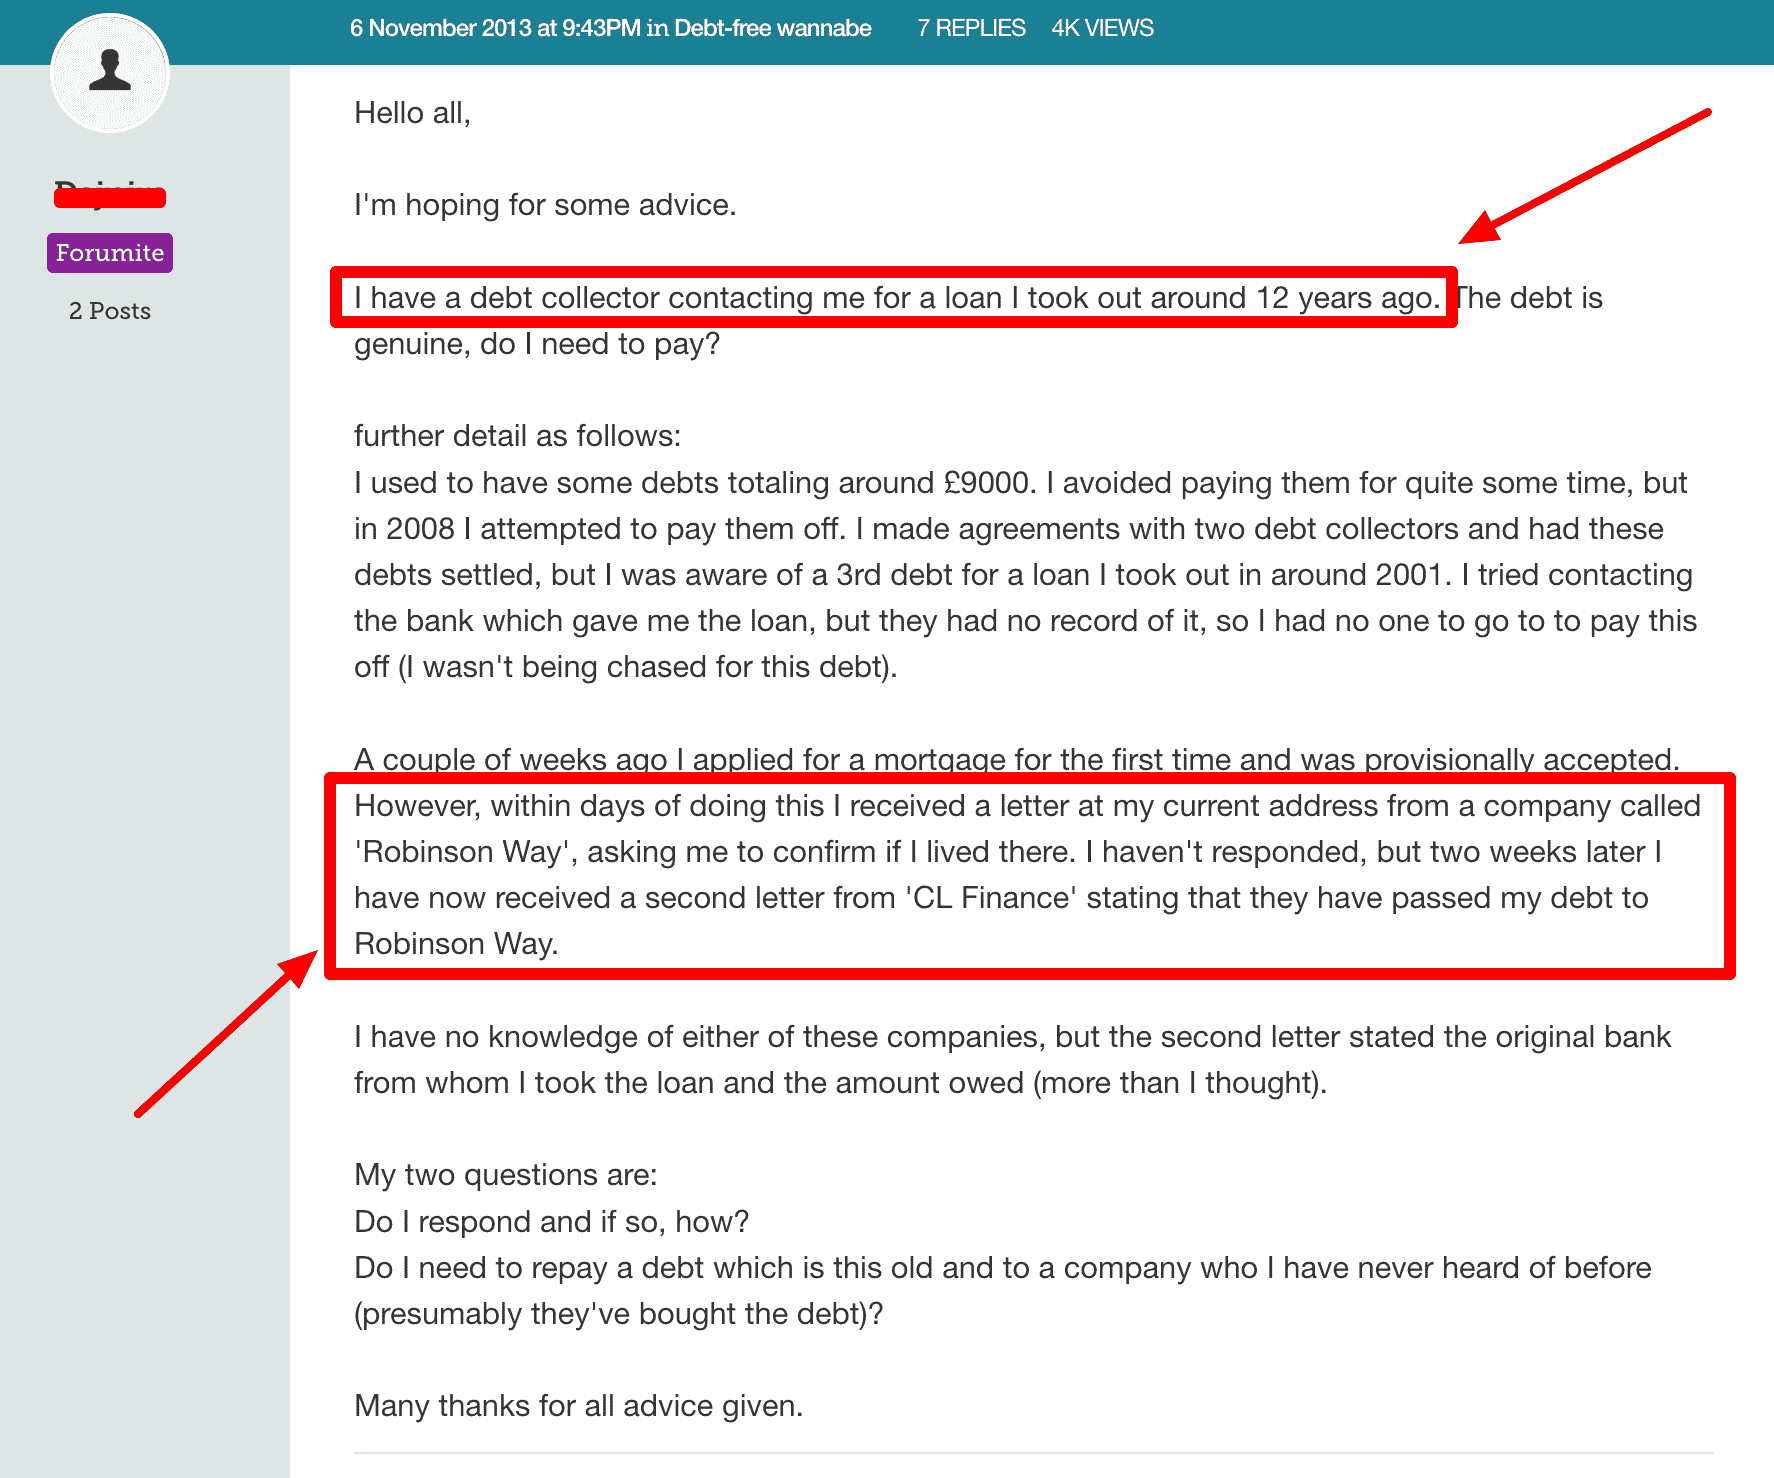
A collection letter does not by itself prove that a debt is enforceable. Limitation and prescription rules depend on the debt, where you live, payments or acknowledgements and whether court action has already been taken. Get free debt advice before paying or admitting liability for an old debt, and never ignore court papers.
Judge & Priestley Contact Details
| Phone: | 020 8290 7400 (debt account enquiries) |
| Fax: | Check current contact methods on the firm’s website. |
| Address: | Justin House, 6 West Street, Bromley, Kent BR1 1JN, DX 117600 BROMLEY 7 |
| Email: | [email protected] |
| Website: | https://www.judge-priestley.co.uk/ |
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Summary
Judge & Priestley provides debt recovery and litigation services for a range of clients. Receiving a solicitor’s letter is a reason to check the account and respond promptly, not proof that the debt is correct or that judgment has already been entered.
References





