Are You Owed Money Ltd: checking a demand and making a complaint


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
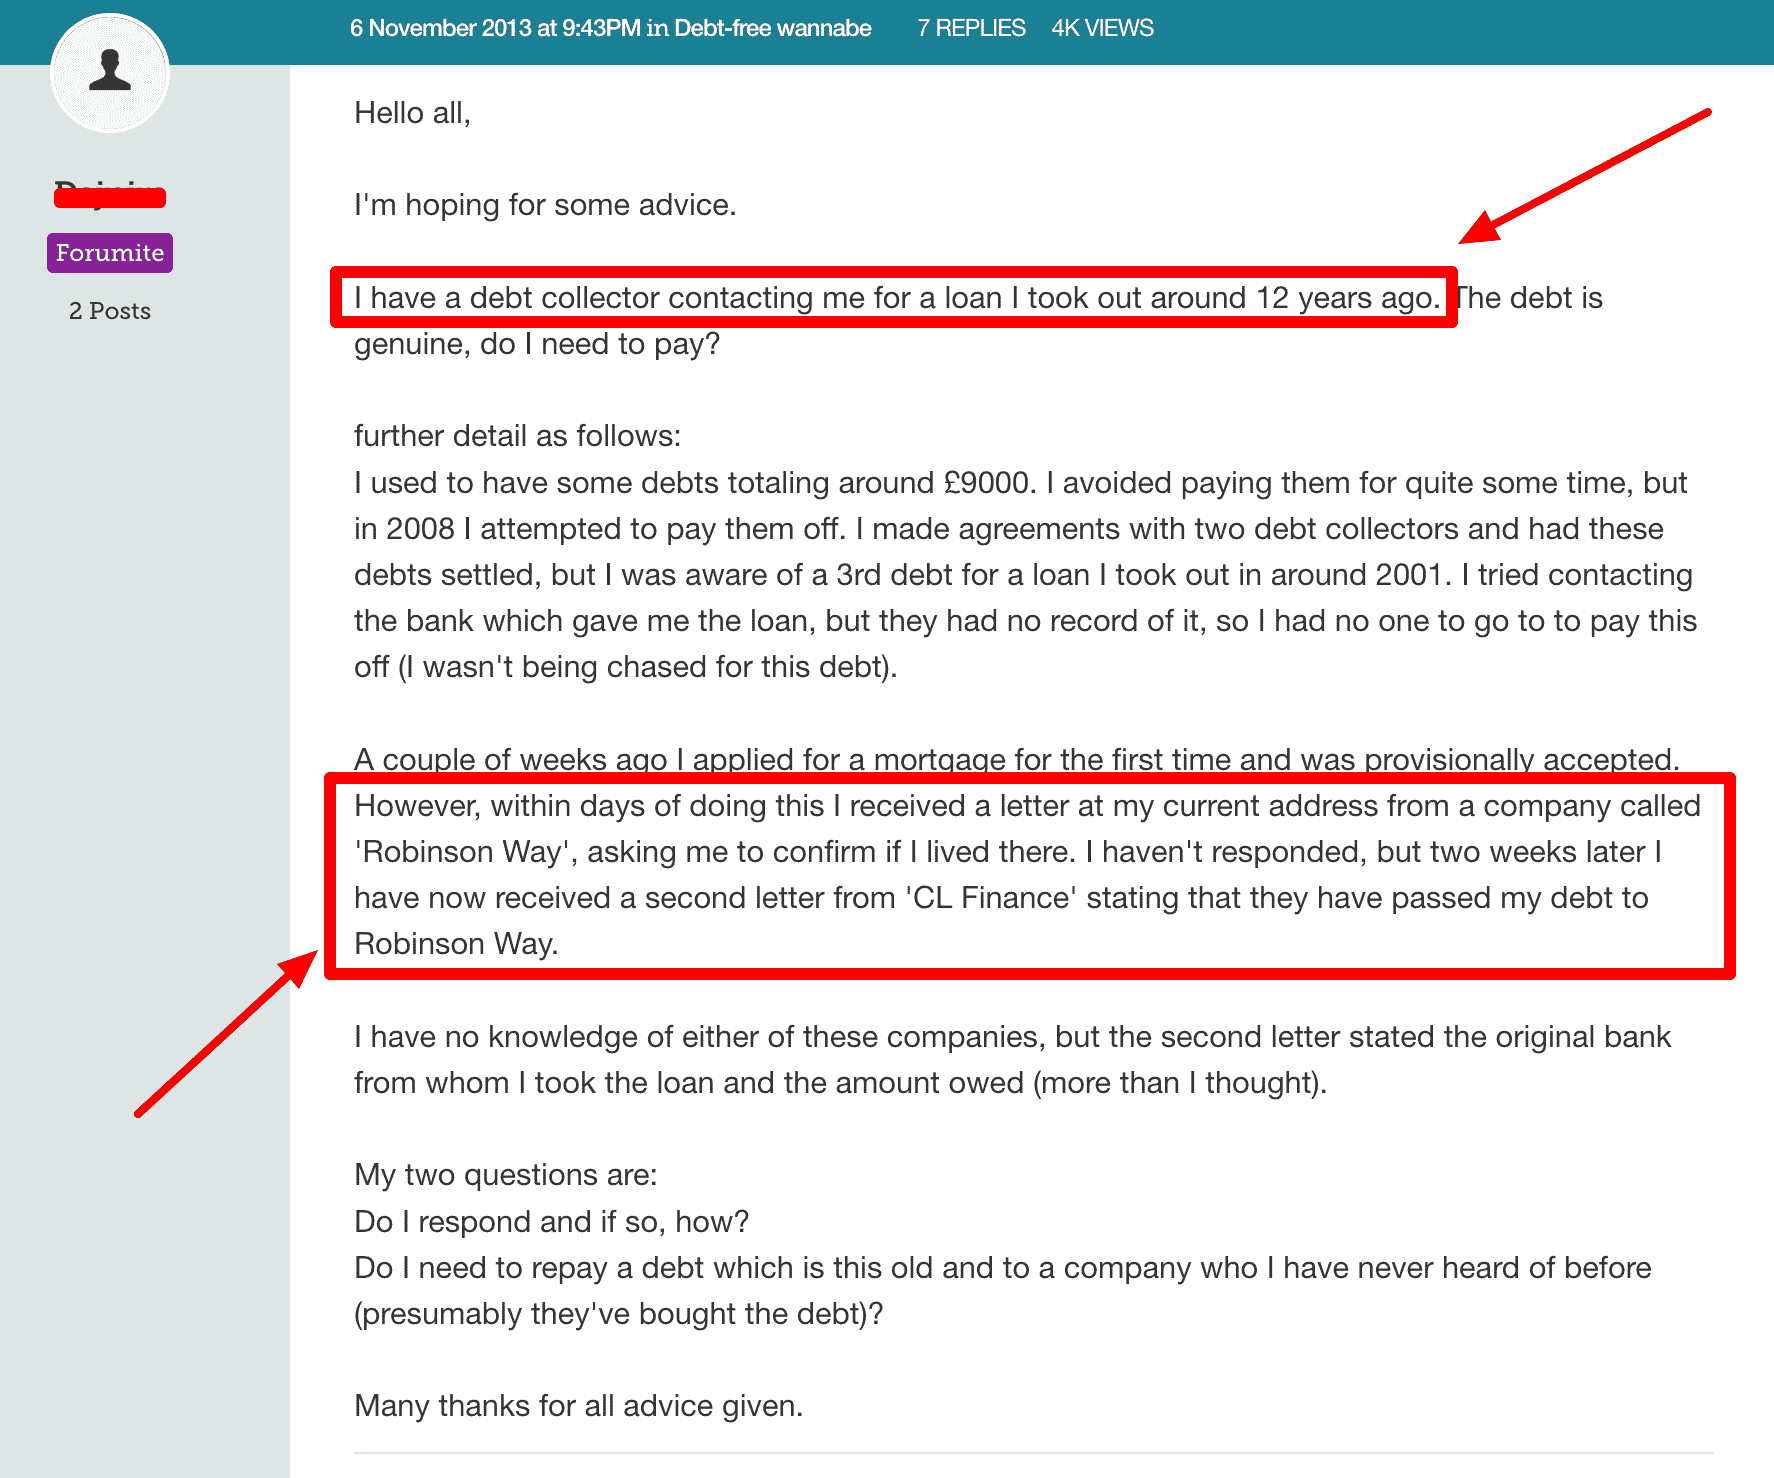
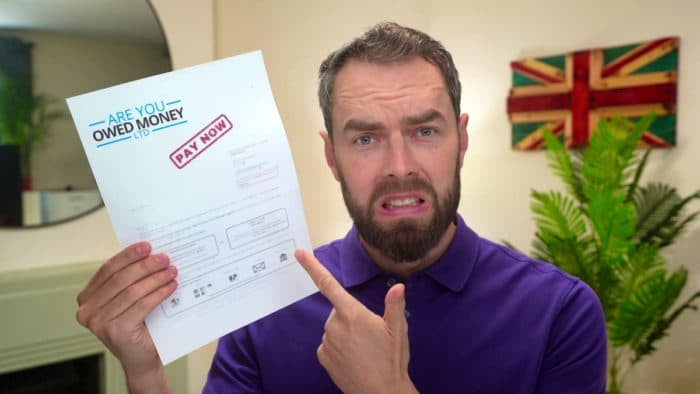
Have you received a letter from Are You Owed Money Ltd? You may be feeling confused about where this debt has come from or if it’s real. You may also be worried about if you should pay or what happens if you can’t. Don’t worry, you’re not alone, and we’re here to help.
This guide explains how to check a demand and respond if you dispute the balance or cannot afford it.
- Understand who Are You Owed Money Ltd are.
- Check if the debt is real and if it is owed by you.
- Learn what happens if you don’t pay.
- Find out ways to deal with the debt, even if you can’t afford to pay it.
- Discover how to stop them from chasing you.
A collection letter can be worrying. Check the sender, creditor and account details before sharing information or making a payment.
Let’s dive in and explore your options.
Have you received a letter?
Are You Owed Money Ltd provides debt-recovery services. A letter may request payment, identify a dispute or warn of proposed court action; read the specific document and its deadline.
The required pre-action steps depend on the debt. The Debt Claims Protocol usually gives an individual at least 30 days to reply to a business’s letter of claim. A Consumer Credit Act default notice is a separate requirement for specified enforcement steps on relevant regulated agreements, not a universal letter sent after every letter of claim.
How do I Verify the Debt?
If you have received debt letters from Are You Owed Money, but aren’t sure if they’re legit, what do you do?
From my experience, the best thing to do is ask for proof that the debt is yours. I have a free ‘prove it’ letter template that you can use to help you write to Are You Owed Money and request evidence that you are liable for the debt that they are chasing.
Explain a dispute and request an itemised balance and evidence of liability. A valid or potentially valid dispute within FCA consumer-credit rules must be investigated with recovery paused, but a generic evidence request does not cancel a debt, override a court order or extend a court deadline.
Responding promptly can help resolve a dispute or agree an affordable arrangement, but does not guarantee that charges or proceedings will stop.
Should you pay?
Not ignoring Are You Owed Money Ltd and paying them are two completely different things. Although you shouldn’t ignore them, you don’t have to pay them straight away. There are things you can do instead, depending on your situation.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
What can you do instead?
Before paying Are You Owed Money Ltd, you should check that the debt is still enforceable and ask them to prove the debt. Here are the details:
#1: Check if the debt is still enforceable
Limitation depends on the debt, jurisdiction, when a claim could first be brought, payments, written acknowledgements and any court proceedings. Many ordinary contract debts have a six-year period in England and Wales; Scotland has different prescription rules. Get advice before acknowledging or paying an old disputed debt. See related guidance.
#2: Ask them to prove it
Request an itemised balance, the original creditor’s details and evidence supporting liability and the collector’s authority. A signed original agreement is not required for every type of debt, and an evidence request does not extend a court deadline.
If they do prove your debt you should consider paying in full, a payment plan, a settlement offer, or even a debt solution.
Can you ignore them?
Do not ignore a letter of claim or court papers. A creditor may issue a claim and, if the procedural conditions are met, request default judgment when no response is filed. Enforcement requires the relevant legal authority; it is not an automatic power of an ordinary collector.
You might hear stories of people ignoring debt collection agencies and getting away without having to pay. Although this is a possibility, it’s a risky strategy.
Are they bailiffs?
An ordinary collection agent has no bailiff powers. They may ask to visit but cannot force entry or seize belongings. A separately authorised enforcement agent has different powers under the relevant warrant, writ or other authority.
Can they take you to court?
Who can bring a claim depends on who legally owns the debt and the representative’s authority. Check the named claimant, any assignment notice and the evidence rather than assuming the collection company is always or never the claimant.
Treat a genuine legal warning seriously and follow the stated response procedure. This article has no evidence that a particular threat by this firm is made without an intention or legal basis to proceed.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
How can you check the firm and raise a complaint?
The AYOM website identifies Are You Owed Money Ltd as its operator. That does not authenticate every message using its name: verify contact and payment details independently before paying.
A complaint about fees or service does not, by itself, establish fraud. Compare the agreed terms, invoices and work provided, then use the firm’s complaints process or seek independent advice.
The review shown below is an individual customer’s account. Its allegations have not been independently established here: See related guidance.
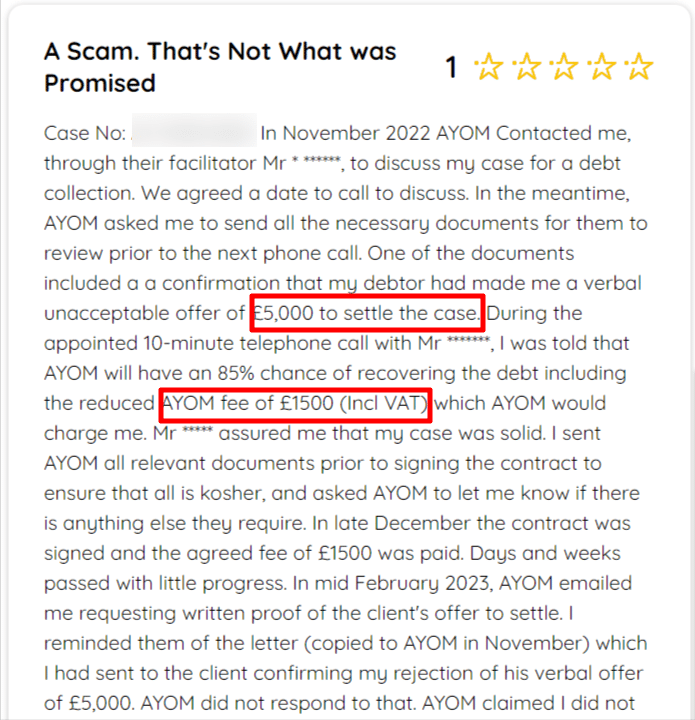
A reported change in a quoted fee does not, on its own, prove dishonesty. Ask for the fee basis and cancellation terms in writing.
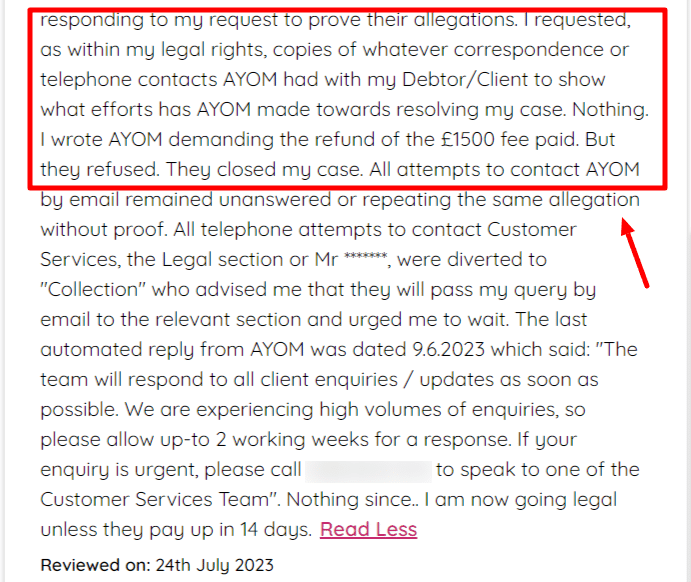
Do not treat the review as a finding that the company committed advance-fee fraud. If you suspect an impersonator or unauthorised payment, contact your bank promptly and report the circumstances through the appropriate fraud-reporting route.
Online reviews can help identify questions to ask, but they are not a substitute for checking the company, the contract and the evidence in your own case.
For help with an unaffordable or disputed debt, the following charities offer free advice. A complaint about a debt-recovery service you purchased may also need consumer or legal advice.
Will They Give Up Chasing?
A collection letter does not by itself prove that a debt is enforceable. Limitation and prescription rules depend on the debt, where you live, payments or acknowledgements and whether court action has already been taken. Get free debt advice before paying or admitting liability for an old debt, and never ignore court papers.