


Churchill Recovery Solutions: Debt Letters and Your Options


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
A debt letter can be worrying. Keep the correspondence, check the creditor and balance, and note any response deadline. Free independent debt advice is available.
In this guide, we’ll help you understand:
- What Churchill Recovery Solutions Limited is.
- How to check if the debt they say you owe is really yours.
- Ways you can stop Churchill Recovery from reaching out to you too much.
- Options for setting up a plan to pay off your debt or possibly even writing it off.
We know how scary it can be to get letters from debt collectors. Some of us have even been in your shoes before so we understand that you’re feeling worried about where this debt came from or if you’re not sure if you should pay.
Here’s how to deal with your Churchill Recovery debt and take control of the situation.
Have you received a letter?
A collection demand is not necessarily a formal Letter of Claim. Read the document carefully, check who the creditor is and respond by any stated deadline. If court papers arrive, follow the court’s deadline even while you are disputing the account or waiting for documents.
However…
Keep a record of any conduct you consider misleading, threatening or excessive. A lawful warning of possible court action is different from pretending to have powers the firm does not possess. A complaint should identify the actual words, dates and evidence.
Ask for proof that you owe the debt
There may be a chance you don’t owe money at all! Instead of paying straight away, you can ask Churchill Recovery Solutions Debt Collection to provide proof that you owe the debt. This is also beneficial if you think they’ve got the wrong person.
You can use my free ‘prove it’ letter template if you need some guidance or aren’t sure where to start.
The evidence that is sent back to you has to be clear and show that you are liable for a debt with your original creditor. This could be your original credit agreement, but can be other documentation about your debt.
If you dispute the debt, explain why and request an itemised balance and evidence of liability. For recovery covered by FCA consumer-credit rules, a valid or potentially valid dispute must be investigated and recovery paused. A generic proof request does not cancel a debt, override an existing judgment or extend a court deadline.
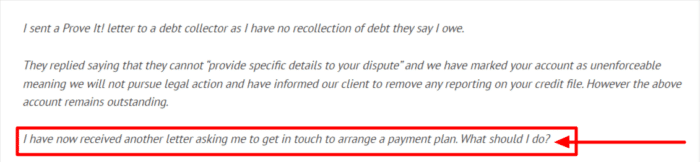
A forum post cannot establish whether this particular debt is payable. Do not ignore a further letter solely because an earlier document request went unanswered, especially if it contains a formal pre-action or court deadline.
Keep copies of requests and replies. If a claim is issued, submit the appropriate response or defence on time; keeping a letter for a judge does not itself defend a claim.
» TAKE ACTION NOW: Fill out the short debt form
Could a time limit affect this debt?
Many ordinary unsecured debts have a six-year limitation period in England and Wales or a five-year prescription period in Scotland. The start date, debt type, relevant payments or acknowledgments and court action matter. Ask an adviser to check before paying or admitting liability, and respond to court papers on time.
See if your debt has become too old to be recovered by reading this guide.
Should you pay?
If you dispute the debt, explain why and request an itemised balance and evidence of liability. For recovery covered by FCA consumer-credit rules, a valid or potentially valid dispute must be investigated and recovery paused. A generic proof request does not cancel a debt, override an existing judgment or extend a court deadline.
Check the account and independently verify the payment destination first. If the debt is enforceable and affordable after essential costs and priority debts, consider payment or an agreed plan. Do not borrow further or miss essential bills simply to meet a collection demand. Prepare a budget covering essential living costs and priority debts first. Propose only instalments you can afford, and obtain written acceptance and confirmation of any interest or action being paused. An offer alone does not guarantee agreement or stop a court claim.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
What Happens If I Don’t Pay?
The consequences depend on the type of debt, its enforceability and what action the creditor takes.
- The creditor may send reminders or a formal demand.
- Missed payments may lead to a default, subject to the account and applicable notice requirements.
- Check who currently owns the account and whether the firm is collecting for that creditor or has bought the debt. A collection letter alone does not establish liability, and a transfer does not automatically change the amount legally due.
- The creditor, or solicitors acting for it, may bring a court claim if entitled to do so. Only the court can issue a judgment. A claim form is not a CCJ: respond within its deadline, as judgment can be entered in default without a hearing.
Are they bailiffs?
When acting as an ordinary debt collector, Churchill has no bailiff powers to force entry or seize goods. Its website also describes utility-warrant work: a separately authorised warrant for access to a meter is different from ordinary collection and is subject to energy-sector rules and safeguards. Check the visitor’s role and the specific authority relied on; do not assume that every utility visit is merely a collection visit.
Keep a record of any conduct you consider misleading, threatening or excessive. A lawful warning of possible court action is different from pretending to have powers the firm does not possess. A complaint should identify the actual words, dates and evidence.
Customer reviews
These are individual reviews reproduced from an earlier version of this article. They are not a current representative survey or verified findings about the firm. Your response should depend on your account and the evidence.
“I spoke to these guys for the first time after receiving a letter. I spoke politely to what can only be described as a “jumped-up aggressive man”. He wouldn’t listen to me and you would think I personally owed him some money or something. Rude, unprofessional and aggressive.”
- Ross H (Google review)
“Completely unprofessional. Shouting at me on the phone telling me they “don’t care” and I’m “not a customer”. Attempting to bully me to acknowledge a debt that may not be mine.”
- Sophie (Google review)
FCA consumer-credit recovery rules apply where the account and activity fall within their scope. They require appropriate treatment of customers in financial difficulty, but do not guarantee acceptance of a particular repayment plan. Utility work has additional rules and safeguards.
Can I write off my debt?
Debt solutions have eligibility rules, costs and consequences. Get free independent advice before deciding whether a solution that can write off included debt is suitable.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Can I stop them from contacting me?
State your reasonable preferences for how, when and where you are contacted, and explain any health or accessibility needs. FCA-regulated recovery must give those preferences due regard. This is not an absolute right to prevent every call or required notice.
How do I complain?
If you think that Churchill Recovery has been unreasonable or behaved inappropriately, you can make a complaint. You can also make a complaint if you feel that they have broken any of the Financial Conduct Authority’s (FCA) guidelines.
Make your first complaint to Churchill Recovery so that they have the chance to sort out the issue themselves. Fortunately, Churchill Recovery have a detailed process on their complaints page on their website. If you feel that they have not taken your complaint seriously enough or have not addressed your issue properly, you can escalate matters.
Complain to the business first. If the activity falls within the Financial Ombudsman Service’s remit, you can normally escalate after a final response or eight weeks without one, usually within six months of the final response. The Ombudsman can require redress, such as compensation or correcting records; it does not fine firms or remove their authorisation.
Checking for Other Debt Collectors
There are a lot of ways to get into debt. In fact, it’s not uncommon to owe money to several companies at once.
Perhaps you have a mortgage, a car loan, a couple credit cards and an item or two you bought on buy-now-pay-later schemes. It’s easy to lose track.
That’s why it’s important to regularly check your credit report and bank statements to make sure you haven’t missed anything.
A sold debt may appear under a new creditor name on your credit report, but not every debt or collector is reported to every credit reference agency.
Some of the debt collectors you’re most likely to come across are PRA Group, Lowell and Cabot Financial.
How can I contact Churchill Recovery about outstanding debts?
Whether you’re looking to talk about how much debt you have or to adjust your monthly repayments, you can easily contact Churchill Recovery on:
| Address: | Suite 5a, Stanley Grange Business Village, Ormskirk Road, Knowsley Village, Merseyside L34 4AR |
| Registered office | C/O Pm+M Waterfold House, Waterfold Business Park, Bury, Lancashire, BL9 7BR |
| Contact number: | 0333 320 0748 |
| Email: | [email protected] |
| Registration number: | 04785274 |
| Website: | https://www.churchillrecoverysolutions.co.uk/ |





