


Kearns Solicitors Debt Letters: How to Respond


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
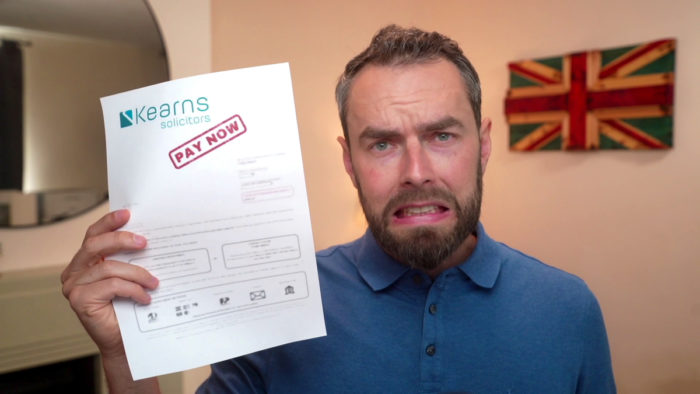
Did you get a letter from Kearns Solicitors about debt? Are you unsure if you should pay? You’re in the right place. Many people visit our website for help with debt questions.
In this article, we’ll help you understand:
- Who Kearns Solicitors are.
- How to deal with Kearns Solicitors debt collectors.
- How to know if the debt is really yours.
- What to do if you can’t afford to pay.
- How to stop Kearns Solicitors from chasing you.
Research shows that 64% of UK adults find interactions with current debt collectors stressful1. So we understand how you feel.
Don’t worry! Our team has lots of experience dealing with debt collectors. So, we’re here to provide helpful advice.
Let’s get started!
Have you received a Kearns Solicitors letter?
Not every letter from Kearns Solicitors is a formal letter before claim. Check its heading and enclosures. Where the Debt Claims Protocol applies to a business claiming from an individual, the letter of claim normally gives 30 days to reply using the enclosed reply form.
A warning of court action should be taken seriously. It must not misrepresent the legal position; this article does not establish that a particular threat is a scare tactic.
However, there is still a chance Kearns Solicitors could help their client take you to court over the arrears.
So, your first question is probably…
Should you pay?
Despite the threat of court action, you shouldn’t just give in and pay Kearns Solicitors straight away, unless you know about the debt and wish to pay it anyway.
Reply to a letter of claim using the appropriate form and explain any dispute, request for documents or need for debt advice. If court proceedings have already begun, use the court’s response procedure.
Requesting information does not cancel the debt or automatically extend a court deadline. If you have the wrong person or account, explain the error promptly and keep evidence.
Your Rights With Debt Collectors
Kearns is a firm of solicitors. It must follow applicable professional and consumer-credit rules and must not use misleading threats or unfair pressure.
Here’s a quick table that explains what debt collectors can and can’t do. If you want to learn more about your rights, make sure to check out our detailed guide.
| Debt collectors may | Limits and protections |
|---|---|
| Contact you to seek payment | For regulated consumer credit, contact must be at reasonable times and respect reasonable requests about when, where and how you are contacted. |
| Ask to discuss the debt at a home visit | A collector has no bailiff powers, cannot force entry or take goods, and should leave when asked. |
| Explain possible court action | They must not mislead you about their powers or threaten action they cannot lawfully take. |
| Discuss an affordable repayment or settlement | Get agreed terms in writing and obtain free advice if you dispute the debt or cannot afford payments. |
| A creditor may seek a separate court enforcement order | A CCJ alone does not give a collector access to your bank account. A third-party debt order requires a separate court process. |
| A creditor may assign a debt | Check who owns it and who is authorised to collect; do not disclose payment details to an unverified caller. |
| Make proportionate follow-up contact | Harassment is prohibited. Requests about contact must be considered; necessary legal notices may still be sent. |
Ordinary debt collectors cannot force entry or seize goods. For regulated consumer-credit collection, workplace visits generally require consent, contact must be reasonable and debt information should not be disclosed unnecessarily to unrelated people. Authorised representatives and court enforcement involve different rules.
How the introduction works
The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.
Options depend on your circumstances. You decide whether to proceed.
Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
Ask them to prove your debt
Ask for the evidence relevant to your dispute, rather than relying on a generic demand for a signed agreement. Useful checks include:
- What evidence has already been supplied, including the account terms, balance and payment history
- Whether a limitation defence or an existing court order changes the next step
If you dispute the debt, explain why and ask for an itemised balance and evidence of liability. For recovery covered by FCA consumer-credit rules, a valid or potentially valid dispute must be investigated and recovery paused. A generic proof request does not cancel the debt, override an existing court order or extend a court deadline. Statutory consumer-credit information requests have separate requirements and do not apply to every debt.
Do not ignore later letters or court papers while waiting for evidence. Keep your correspondence and obtain advice about the correct response. An unanswered proof request does not automatically defeat a claim.
Debt advice: Continue to the debt enquiry form
Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.
Or tell them your debt is statute-barred
In England and Wales, many ordinary contractual debts have a six-year limitation period from when the creditor can first sue. A payment or relevant written acknowledgment before expiry can restart it, and a claim issued in time or an existing judgment changes the position. Age alone does not prove a debt is statute barred. Scotland has different prescription rules; get advice before paying or acknowledging an old disputed debt, and respond to court papers on time.
You should check to see if your debt qualifies as statute-barred by reading our detailed guide, and getting a second opinion from a debt charity. And then tell Kearns if it has become too old to be collected.
The debt was proved – should I pay?
If Kearns Solicitors prove you owe the debt then you should probably pay. Not doing so could end in legal action and further expense for you.
About The Debt Advice Service
Use the enquiry form to request a call about your circumstances and available options. You decide whether to proceed.

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
Other Debt Collectors to look for on your Credit Report
There are hundreds of debt collectors in the UK and they each collect for different companies.
It’s surprisingly easy to not notice that you’re in a debt collector’s crosshairs.
I’d suggest you spend time checking your credit report. A sold debt may appear under a new creditor name on your credit report, but not every debt or collector is reported to every credit reference agency.
Some of the biggest to look out for include Cabot, PRA Group, and Lowell.
So if you see anything relating to their names, then you’ll need to investigate further.
Kearns Solicitors Debt Recovery reviews
Upon reading the Kearns Solicitors reviews online, you’ll get mixed messages. But the reviews also suggest that Kearns Solicitors will sometimes work with their client to escalate the debt collection process to the courts.
This means that any legal threats are not always made to simply scare you into paying. Take a look at this review:
“Well, they have taken action against me so I may well be a little bit biased. Not a massive fan. However, I have had a couple of communications with them and have found them fairly responsive.”
- The Fuzzy Scrapper (Google review)
The creditor may instruct Kearns to bring a claim. A judgment is not automatic: you can admit an amount due, dispute the claim or seek advice about time to pay using the correct procedure. Enforcement requires an unpaid judgment or other lawful authority and the appropriate application.
If you receive court papers, focus on their deadline even if earlier correspondence or a complaint remains unresolved. Raise the complaint with the firm first. You can report serious professional misconduct by a solicitor to the Solicitors Regulation Authority, but it cannot decide the underlying debt dispute or stop a court case. The Legal Ombudsman generally deals with service complaints from eligible clients, not complaints about an opponent’s solicitor. Financial Ombudsman eligibility depends on the activity and complainant.
Kearns Solicitors Contact Details
| Address: | Kearns Solicitors, Brecon House,3 Caerphilly Business Park, Caerphilly, CF83 3GQ |
| Telephone: | 02920808668 |
| Fax: | 02920 808667 |
| Email: | [email protected] |
| Website: | https://www.kearns.co.uk/ |
References





