


Stirling Park Sheriff Officers: Your Rights in Scotland


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
If you’ve received a surprising letter from Stirling Park Debt Collection, don’t worry -you’re at the right place.
A demand can be worrying. Check the document and get Scottish debt advice if it is disputed or unaffordable.
This guide explains the difference between informal collection and sheriff-officer enforcement.
In this article, we’ll explain:
- How to check if the debt really is yours.
- What to do if Stirling Park contacts you.
- How to find out if their claim can be enforced.
- What your options are if you owe an enforceable debt to Stirling Park.
- How ignoring a debt to Stirling Park might affect you.
We know that dealing with debt collectors can be tough because some of our team have been there too. But with the right information and a bit of guidance, you can manage this situation.
What should I do if they contact me?
First of all, you should verify that it is genuinely Stirling Park who are contacting you. Secondly, you should verify exactly why they are contacting you. Thirdly, you should verify if their claim is enforceable.
Only once you have taken all of these steps should you decide what to do next. This will depend on the exact situation.
Remember, you must take action but it’s important to keep calm when you do. There is always a way forward.
Your Rights
Understanding your rights when Stirling Park contacts you is crucial to prevent unfair treatment, harassment, or any other unwanted situations.
Stirling Park provides debt collection and sheriff-officer services. Ordinary debt collectors cannot seize your belongings, but sheriff officers can exercise the powers authorised by Scottish law and the court. Check which role applies to your letter.
| Debt collectors may | Limits and protections |
|---|---|
| Contact you to seek payment | For regulated consumer credit, contact must be at reasonable times and respect reasonable requests about when, where and how you are contacted. |
| Ask to discuss the debt at a home visit | A collector has no bailiff powers, cannot force entry or take goods, and should leave when asked. |
| Explain possible court action | They must not mislead you about their powers or threaten action they cannot lawfully take. |
| Discuss an affordable repayment or settlement | Get agreed terms in writing and obtain free advice if you dispute the debt or cannot afford payments. |
| A creditor may seek a separate court enforcement order | A CCJ alone does not give a collector access to your bank account. A third-party debt order requires a separate court process. |
| A creditor may assign a debt | Check who owns it and who is authorised to collect; do not disclose payment details to an unverified caller. |
| Make proportionate follow-up contact | Harassment is prohibited. Requests about contact must be considered; necessary legal notices may still be sent. |
» TAKE ACTION NOW: Fill out the short debt form
Does the debt belong to you?
If the debt is not yours or has already been paid, raise the dispute promptly with Stirling Park and the creditor. Ask for the balance and the decree, summary warrant or other authority relied on. A generic proof request does not suspend court deadlines or existing enforcement.
Dear Stirling Park, I dispute the debt referred to in your letter dated [date], reference [reference], because [reason]. Please identify the creditor, provide an itemised balance and explain the legal authority for the requested payment or enforcement. Please investigate and confirm whether action will be paused. I do not admit liability for the disputed amount. Yours faithfully, [name].
You can send this by email or letter. If you send it by email, then you may want to think about the email address you use. In fact, you may want to create a specific email address just for dealing with Stirling Park. If you send it by letter, then it’s advisable to use recorded delivery. In either case, it’s usually perfectly reasonable just to supply the reference number, especially if you don’t have a proper scanner and/or printer.
Think very carefully before including your phone number or handing it over if Stirling Park requests it.
The evidence needed depends on the debt. A council tax summary warrant is not a consumer credit agreement. For a consumer-credit account, relevant documents may include:
- Credit application+Loan Agreement
- Detailed statement of account
- Copy of default notice
- Copy of formal demand
If ownership changed, ask who now owns the account and for relevant assignment information. Not every transfer requires fresh consent from the borrower.
No response does not automatically close the case or cancel the debt. Keep your correspondence, check any credit-file errors and obtain advice if further demands or legal papers arrive.
If Stirling Park does not respond but continues to make collection attempts, you should follow up your original letter. Again, there are plenty of online templates you can follow. Here is a suggestion.
Dear Stirling Park, COMPLAINT. On [date] I disputed the account [reference] for [reason] and requested evidence. Please investigate, explain your response and correct any inaccurate records. Please also confirm your complaints process and the appropriate escalation route. Yours faithfully, [name].
Respond to court documents by the stated deadline; an evidence request is not a substitute for a court response.
Get advice promptly on responding to a Scottish court claim or challenging a decree or enforcement step. A Scottish decree is different from a County Court Judgment used in England and Wales.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Is it still enforceable?
Enforceability can depend on several factors, including liability, prescription, court authority and any formal debt protection. Insolvency and age are not the only possible issues.
If the account is included in an insolvency arrangement or other formal protection, tell Stirling Park and your adviser or trustee promptly. Check the precise restrictions and exclusions rather than assuming every form of contact is prohibited.
Dear Stirling Park, Account [reference] is included in [type of arrangement/order] made on [date]. Please contact [adviser/trustee details] and check which restrictions on recovery apply. Please confirm your response in writing. Yours faithfully, [name].
The other reason is a statute-barred debt.
Scotland has its own prescription rules. Many ordinary contractual debts can be extinguished after five years without a relevant claim or relevant acknowledgment, but the start date and exceptions matter. Council tax, tax debts and court decrees do not follow that ordinary five-year rule. A creditor’s letter alone does not restart the period. Get a Scottish debt adviser to check your dates and debt type before making a payment or admitting liability.
Where Scottish prescription extinguishes a debt, the obligation no longer exists. This differs from an ordinary limitation defence in England and Wales. Do not assume a council tax debt or court decree has prescribed after five years.
Keep in mind that not all debts become statute-barred!
Tax debts, council tax and decrees have different rules. Their enforceability cannot be decided using the ordinary consumer-debt checklist.
If you think your debt is statute-barred, then you can use this template for Scotland and this template for the rest of the UK.
When you do owe the debt
If the debt is enforceable, options may include an affordable agreement, court time to pay where available, DAS, or an appropriate insolvency solution. Get advice on the choices available in Scotland.
In turn, you must help yourself and do what you can to help others to help you. In other words, you need to keep your head out of the sand and face reality.
If you can afford to pay off the debt in full without compromising on the essentials you need for a basic standard of living, then it usually makes sense to do so. If you can’t, then it is strongly recommended to seek advice from a professional debt advisor.
An independent money adviser can assess your circumstances, explain Scottish options and help communicate with the creditor. Their involvement does not guarantee a particular outcome or stop every legal notice.
There are two points to remember here. Firstly, it is the job of a debt advisor to help you not to judge you. Secondly, at the end of the day, creditors want as much money as they can get out of you as quickly as they can get it out of you. If you cannot pay the full amount within the requested time-frame, then you can offer to pay a lower amount and/or to pay over a longer period.
If you cannot afford to do that, then you may want to consider a debt solution. There are several debt solutions in the UK, so I recommend seeking specialist advice from a debt charity before you start. Some financial counselling from a professional will help you find out which solution is best for you.
Debt Management Plan (DMP)
A DMP is an informal debt solution that lets you pay off your debts via a single monthly payment.
Because it is informal, it is not legally binding so you are not tied into a DMP for a minimum number of payments.
Individual Voluntary Arrangement (IVA)
An IVA is a formal insolvency option in England, Wales and Northern Ireland; it is not a Scottish debt solution.
Scottish residents should ask an adviser to compare DAS, protected trust deeds, sequestration and informal arrangements.
Eligibility depends on your circumstances and the rules of the particular solution. Do not choose a solution simply because it promises to stop letters.
Trust Deed
A protected trust deed is a Scottish insolvency option with eligibility, asset and contribution rules. It may write off qualifying unpaid debts on successful completion, but it can put your home, car and other assets at risk. It does not automatically protect all property or cover every debt. Get independent debt advice before signing.
A debt payment programme under Scotland’s Debt Arrangement Scheme can freeze interest and protect against covered enforcement while the statutory conditions are met. It normally repays the debts in full. An approved money adviser can explain application-stage protection, existing arrestments and the effect of missed payments.
Debt Relief Order (DRO)
Debt Relief Orders are not available in Scotland. They are available under separate rules in England, Wales and Northern Ireland.
A Scottish adviser can explain whether Minimal Asset Process bankruptcy or another Scottish option fits your circumstances.
The debts covered, asset consequences and discharge conditions differ between solutions.
Bankruptcy
If you have debts but no realistic possibility of ever paying them off, you may need to declare bankruptcy.
Bankruptcy has an unfair stigma attached to it as it may be your only way of getting a financial fresh start. That said, it is a serious financial situation that should not be taken lightly.
Sequestration
Sequestration is the Scottish bankruptcy process. Scotland’s Minimal Asset Process is a route into bankruptcy for people who meet its conditions. Its application fee has been removed. Ask an approved Scottish money adviser to compare it with the alternatives and explain the effects on assets, credit and income.
Thousands have already tackled their debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
When you just ignore it
Respond promptly to a disputed debt, but do not assume a request for proof cancels it. Follow any court or enforcement challenge procedure and seek advice about deadlines.
Ignoring correspondence can lead to further lawful action and fees. The steps available depend on whether Stirling Park is collecting informally or enforcing court authority.
Calls must be reasonable and take account of your circumstances and contact preferences. Direct-marketing hours are not a legal timetable for debt collection. Sheriff-officer visits and execution of court orders have separate rules.
Stirling Park must act lawfully and handle personal information appropriately. A sheriff officer may have powers to serve or enforce court documents that an ordinary collector does not. Legitimate contact with an authorised adviser differs from improper disclosure to an unrelated person.
Your personal information must be handled appropriately. Any added interest or fees must have a lawful basis; ask for an itemised balance if you dispute them.
Will it affect my credit score?
Credit-file effects depend on the type of debt and any reported default or court decree. Merely receiving a collection letter does not automatically create a credit-file entry.
This is because credit companies use your credit file to see if you are a high-risk customer – someone who might not pay back all of their debts promptly.
A Scottish court decree can affect your credit file. A council tax summary warrant does not usually appear on it; enforcement costs and other consequences can still follow.
An error may need active correction. Check the underlying account and any credit-file entry rather than assuming incorrect contact can never affect reporting.
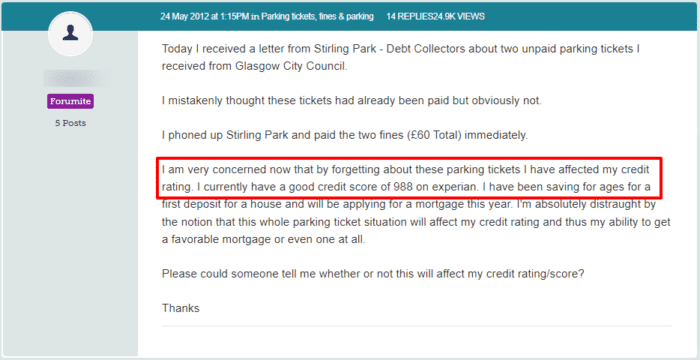
If a council parking penalty has already been paid, provide evidence to both the council and Stirling Park and ask for reconciliation and confirmation that enforcement has stopped. Seek urgent advice if action continues; do not rely on an online example as a guarantee.
Can I Complain?
You can complain about inappropriate conduct or an error. The correct escalation route depends on whether the firm is collecting a regulated credit debt or acting as a Scottish sheriff officer.
Make your first complaint to Stirling Park so that they have the chance to sort out the issue themselves. If you feel that they have not taken your complaint seriously enough or have not addressed your issue properly, you can escalate matters.
Complain to the firm first and keep copies of the evidence. For sheriff-officer conduct, escalation can be to the Society of Messengers-at-Arms and Sheriff Officers or the relevant Sheriff Principal. The Financial Ombudsman Service is not the general complaints body for Scottish court enforcement. A complaint does not automatically stop enforcement.
Stirling Park Contact Details
| Registered office | Stirling Park LLP 25 Bank Street Kilmarnock KA1 1HA |
| Collections telephone | 01563 546518 |
| Collections email | [email protected] |
| Official website | stirlingpark.co.uk |
| Company number | SO300097 |
Other Debt Collectors to look for on your Credit Report
There are hundreds of debt collectors in the UK and they each collect for different companies.
It’s surprisingly easy to not notice that you’re in a debt collector’s crosshairs.
I’d suggest you spend time checking your credit report. A sold debt may appear under a new creditor name on your credit report, but not every debt or collector is reported to every credit reference agency.
Some of the biggest to look out for include Cabot, PRA Group, and Lowell.
So if you see anything relating to their names, then you’ll need to investigate further.
References
Scottish Government: time to pay
South Lanarkshire Council: collection process and Stirling Park contact details





