


Themis Recoveries Debt Letters: Checks, Payments and Complaints


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Received a demand from Themis Recoveries? Check which creditor and account it concerns. Themis Global Limited provides arrears-management and collection services for clients.
In this easy guide, we’ll look at:
- Who Themis Recoveries are and what they do.
- How long debt recovery usually takes.
- How to check if the debt is really yours.
- What to do if you can’t afford to pay.
- Your options to manage or possibly write off some of the debt.
You might be feeling worried or confused — that’s normal. Many people feel the same when they get a letter about a debt they didn’t know about. We understand your concerns, and we’ll give you clear advice to help you decide what to do.
Ask Them to Prove Your Debt
Ask for the creditor’s name, account reference, balance breakdown and evidence that you are liable. For regulated consumer credit debts, a firm must pause recovery while it investigates a dispute on valid or potentially valid grounds. A request for information does not itself cancel the debt or extend a court deadline.
Learn more in our prove-the-debt guide with a free letter template!
Do I need to Pay?
Check the account, enforceability and any specific dispute. Limitation depends on the debt, jurisdiction and dates; a missing original signed document does not automatically mean you owe nothing.
» TAKE ACTION NOW: Fill out the short debt form
They Proved My Debt – Help!
If the balance is valid and enforceable, consider an affordable payment, a written settlement or a repayment arrangement. Allow for essentials and priority bills, and get independent advice if you cannot manage the debt.
A debt solution is a good idea if you have unsecured debts that you can’t manage on your own. There are several options in the UK, so I recommend speaking to a debt charity for some free financial advice before you start any. Their advisors will be able to take a detailed look at your finances and tell you which will work best for you.
I have linked several charities that offer these services for free below.
Debt Management Plan (DMP)
A DMP is an informal debt solution that lets you pay off your debts via a single monthly payment.
Because it is informal, it is not legally binding so you are not tied into a DMP for a minimum number of payments.
Individual Voluntary Arrangement (IVA)
An IVA is a formal insolvency arrangement managed by an insolvency practitioner. Your proposal sets out payments, any assets involved and fees. Once approved, it binds the creditors and debts covered by it and restricts recovery action; it is not a blanket ban on necessary correspondence.
Many IVAs involve payments for five or six years, but the agreed term varies. Qualifying unpaid debt is normally released only on successful completion. An IVA affects your credit record, may involve assets or home equity, and can fail if its terms are not met.
IVA suitability depends on your debts, affordable contributions or available assets, fees and creditor approval. There is no universal rule that you must owe several thousand pounds to more than one creditor. Get independent debt advice and compare other options before agreeing to an IVA.
Trust Deed
IVAs are not available in Scotland. A Scottish money adviser can compare a protected trust deed, the Debt Arrangement Scheme, sequestration and informal arrangements; a trust deed is not compulsory.
A protected trust deed is a Scottish insolvency arrangement, usually lasting at least four years of contributions. It can discharge qualifying unpaid debt on successful completion, but fees apply and your home or other assets may be at risk. Covered creditors cannot pursue payment outside it, but can still send required documents.
Debt Relief Order (DRO)
In England and Wales, a DRO may suit an eligible non-homeowner with low surplus income, limited assets and qualifying debts within the £50,000 limit. Detailed income, asset, vehicle and residence rules apply. An approved debt adviser checks eligibility and submits the application to the Insolvency Service.
During the usual 12-month DRO period, recovery of listed qualifying debts is restricted and you generally do not pay those debts. Continue paying essential ongoing bills and excluded debts. A DRO does not prohibit every required creditor notice.
A DRO normally lasts 12 months. If it remains in force, the qualifying debts listed in it are normally discharged at the end. You must report relevant changes and continue paying ongoing bills and excluded debts, such as court fines and student loans.
Bankruptcy
If you have debts but no realistic possibility of ever paying them off, you may need to declare bankruptcy.
Bankruptcy has an unfair stigma attached to it as it may be your only way of getting a financial fresh start. That said, it is a serious financial situation that should not be taken lightly.
Sequestration
Sequestration is the Scottish bankruptcy process. Scotland’s Minimal Asset Process is a route into bankruptcy for people who meet its conditions. Its application fee has been removed. Ask an approved Scottish money adviser to compare it with the alternatives and explain the effects on assets, credit and income.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Can They Take Me to Court?
An entitled creditor may bring court proceedings. There is no reliable basis here to assume that a particular threat is rare or will not be acted on.
Read any legal notice carefully and meet its deadline. Ask an adviser to distinguish a collection letter, a letter of claim and an issued court claim.
A County Court claim is an application to court; a CCJ is a judgment. They are not the same document or stage.
In England and Wales, the Debt Claims Protocol normally requires a business claiming a debt from an individual to send a letter of claim and allow at least 30 days for a response before proceedings. Other claims, jurisdictions and issued court papers have different rules and deadlines.
Now is the time to get legal advice. I have linked some charities at the bottom of the page that will offer these services for free.
Court action can add costs and affect your credit record if judgment is entered. Do not assume that the cost to the creditor makes proceedings unlikely.
You can request an affordable arrangement, but acceptance of a particular offer is not guaranteed. Keep the terms of any agreement in writing.
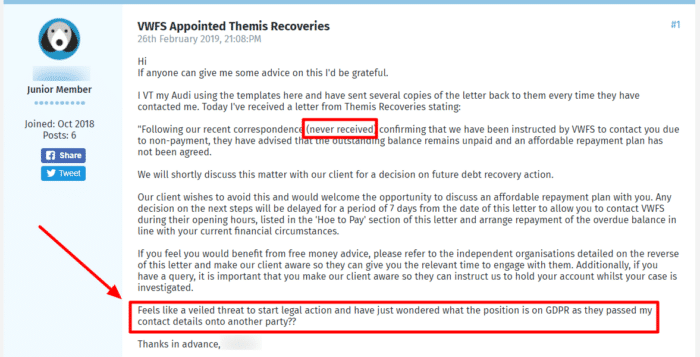
If you receive a similar letter, verify it and respond appropriately. Seeking an arrangement does not itself extend a court deadline or stop a claim.
Data sharing requires a lawful basis, but that basis is not always consent. Read the creditor’s and collector’s privacy notices and challenge inaccurate information or an improper disclosure. A referral clause alone does not establish that every use of your data is lawful.
How Can I Stop the Letters?
Ask for appropriate contact arrangements, dispute any error clearly and seek advice if the balance is unaffordable. Resolving a dispute or entering a debt solution may restrict collection, but it does not guarantee that every required notice stops.
The evidence, payment and complaint sections explain the main response options. Respond separately to any court papers within their deadlines.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
How Do I Complain?
If you think that Themis Recoveries has been unreasonable or behaved inappropriately, you can make a complaint. You can also make a complaint if you feel that they have broken any of the Financial Conduct Authority’s (FCA) guidelines.
Make your first complaint to Themis so that they have the chance to sort out the issue themselves. If you feel that they have not taken your complaint seriously enough or have not addressed your issue properly, you can escalate matters.
Complain to the business first. If the activity falls within the Financial Ombudsman Service’s remit, you can normally escalate after a final response or eight weeks without one, usually within six months of the final response. The Ombudsman can require redress, such as compensation or correcting records; it does not fine firms or remove their authorisation.
Staying On Top Of Your Debts
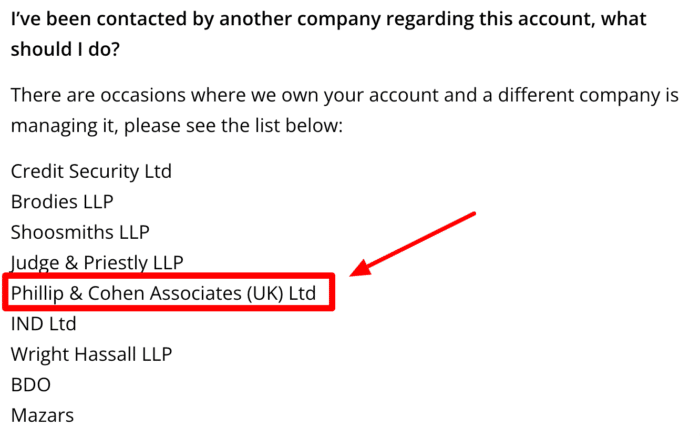
A letter may come from the original creditor, a debt purchaser or a separate collection agency. Check the business name and contact details against reliable records, and ask it to explain who owns the debt and its authority to collect. Keep earlier correspondence so you can trace any change of owner or representative.
- Robinson Way will sometimes contact you under the name Hoist Finance.
- Cabot Financial Group recently bought Wescot Credit Services
- Credit Style communicate as both Credit Style and CST Law.
- Lowell Financial also owns Overdales and collects debts under both names.
Themis Global Contact Details
| Company | Themis Global Limited; company number 09641323 |
| Registered office | Ferneberga House Alexandra Road Farnborough Hampshire GU14 6DQ |
| Customer and complaint telephone | 0345 218 5225 |
| [email protected] | |
| Official website | themisglobal.co.uk |





