


How Much Will Debt Collectors Settle For? Making an Offer


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
There is no fixed percentage that every debt collector will accept. A settlement depends on the account, your circumstances and the creditor’s decision.
In this article, we’ll help you understand:
- How debt collectors decide how much to settle for.
- Ways to make a good settlement offer.
- Tips for talking to debt collectors.
- How debt settlement affects different types of debt.
- The law around debt settlement in the UK.
Check the debt and obtain advice before offering money, especially if it is old, disputed or you may need an insolvency solution.
This guide explains full and final offers and the safeguards to put in place before paying.
Start with your overall budget and priority bills, rather than a target discount.
What is a ‘Full and Final’ Settlement Offer and How Does it Work?
A debt settlement process can seem daunting which is why I suggest you seek advice from a debt expert first.
If you get a lump sum of money through inheritance because you sold an asset or you received a gift from family or friends, you could use it to pay off debt collectors.
It’s a good debt negotiation strategy in certain situations.
Before using a lump sum, consider essential costs, priority arrears and whether another debt solution is more suitable. A general debt statistic cannot determine the right choice for you.
If the lump sum you’ve received is less than the debt you owe, you could opt to make a ‘full and final’ offer to your creditors/debt collector.
A debt collector could agree to receive a lump sum payment, and in return, they may write off the rest of your debt.
A settlement can be useful, but it is not automatically cheaper, easier or more suitable than other options.
Compare it with affordable repayment and any relevant formal solution through free debt advice.
You pay the agreed settlement amount, which may be less than the balance. The creditor must clearly accept what happens to the remainder.
How Do I Make a Settlement Offer?
Settling a debt may seem like a complicated procedure but really, it’s all mostly common sense. That said, there are debt solution strategies that an advisor could walk you through.
Making a fair settlement offer stands a better chance of being accepted.
Work out what you can safely afford to offer after essential costs and priority debts. You do not automatically need to surrender your entire lump sum to a single non-priority creditor.
For several comparable non-priority debts, a common approach is to offer the same proportion of each balance, rather than the same cash amount to each creditor.
For example, suppose that the lump sum of money you have is about 80% of the total debt that you owe. In this case, you should offer each creditor 80% of the total amount that you owed to that particular creditor.
Always remember that before you send any money to creditors, ask them if they accept your offer. Be sure to get their acceptance in writing so that you have proof in case of any dispute in the future.
Make sure you keep all the letters and any other correspondence you have with debt collectors and your creditors. Just in case you need to refer to them in the future.
Keep written acceptance and proof of payment safely for the long term, since a dispute can arise years later.
Do not confuse how long you retain evidence with the separate credit-reporting and limitation rules.
The task requires a lot of micromanaging if you have a lot of creditors.
Every creditor may not be receptive to your offer and they might need convincing.
You’ll probably have to deal with them individually and hopefully, you’ll be able to get them all to agree to your offer. But I suggest you seek debt advice from one of the UK’s debt charities first.
To ask your creditors or debt collectors to accept a full and final settlement offer, use our free letter template.
Once all your creditors have agreed to your offer, be sure to send each of them the agreed-upon amount by the due date.
Make sure to keep proof of payment from each of them just in case a dispute comes up in the future.
» TAKE ACTION NOW: Fill out the short debt form
How Likely is it that My Offer will be Accepted?
This is a difficult question to answer as it varies from person to person.
Acceptance varies. Do not deliberately miss payments or cause a default merely to seek a discount.
If you have been making low monthly payments in the past or no payments at all, your creditors could be happy to receive a lump sum payment even if the amount is less than what’s owed.
A budget and relevant evidence can explain why the offer is realistic. Share necessary information through a verified route; a creditor may still decline.
Transparency in debt settlement is essential.
Clear information helps the creditor assess the proposal; it does not ensure acceptance.
Ask for a written response explaining whether the offer resolves the whole account.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
My Creditor has Proposed a Full and Final Offer, What Should I Do?
Creditors sometimes propose discounted settlements themselves. Verify the sender and read the conditions carefully.
Check the deadline, amount and treatment of the remaining balance before deciding whether the offer is affordable.
Do not take unaffordable new credit, raid essential living money or withdraw pension funds simply to meet a settlement demand. Obtain advice about the wider consequences.
It could also be a good idea to assess the situation and see if you could negotiate with your creditors to bring the settlement down to a more affordable sum.
You can propose a lower affordable amount, but figures such as 40%, 50% or 60% are examples, not standard acceptance rates.
Again, be thorough about your situation and financial information to make them understand that this would be a much better option than you slowly paying off your debt for what could be years.
Last but not least, read the letter they’ve sent you with the utmost care.
Ensure that they have agreed to write off the rest of the debt once you pay off the agreed-upon amount.
Make sure you get the information in writing.
Ordinary collectors must protect your privacy and avoid threatening or misleading conduct. FCA rules require consideration of reasonable contact preferences; they do not impose an absolute ban on every workplace contact or authorised discussion with a representative.
It’s important to know your rights and those of the debt collectors you’re dealing with to have an edge over the situation in case certain terms and not agreed upon. Here’s a quick table summarizing debt collectors’ rights.
| Debt collectors may | Limits and protections |
|---|---|
| Contact you to seek payment | For regulated consumer credit, contact must be at reasonable times and respect reasonable requests about when, where and how you are contacted. |
| Ask to discuss the debt at a home visit | A collector has no bailiff powers, cannot force entry or take goods, and should leave when asked. |
| Explain possible court action | They must not mislead you about their powers or threaten action they cannot lawfully take. |
| Discuss an affordable repayment or settlement | Get agreed terms in writing and obtain free advice if you dispute the debt or cannot afford payments. |
| A creditor may seek a separate court enforcement order | A CCJ alone does not give a collector access to your bank account. A third-party debt order requires a separate court process. |
| A creditor may assign a debt | Check who owns it and who is authorised to collect; do not disclose payment details to an unverified caller. |
| Make proportionate follow-up contact | Harassment is prohibited. Requests about contact must be considered; necessary legal notices may still be sent. |
Possible Drawbacks of Full and Final Settlements
I’ve listed some of the possible drawbacks of making a full and final settlement here:
- You must have enough money to make an attractive offer to creditors
- Creditors could demand you pay the full debt amount
A reduced settlement can be marked partially settled and may affect future lending decisions. Its reporting period depends on whether the account already defaulted.
Will This Settled Debt Show Up in My Credit Report?
Debt settlements are a sigh of relief for any debtor but just like most debt solutions, it’s going to stay in your credit report for a while.
For a reduced full and final payment, the account may show partial settlement with no remaining balance due. Ask how the firm will report it and check the entry afterwards.
It will show other lenders that the complete amount was not paid back by you in order to settle the debt.
A partial-settlement marker can influence a lender’s decision, but the effect varies and does not guarantee rejection.
For a non-defaulted account, a closed-account entry normally remains for six years after closure. For an already defaulted account, settlement should not restart the six years from the original default date.
Keep in mind that if your debt defaulted, then it’s going to stay in your credit file for six years after the date it defaulted.
A registered CCJ has its own reporting rules and can affect credit applications.
A partial settlement does not automatically remove a CCJ. If a judgment already exists, seek advice on recording the agreement and dealing with the judgment record.
Getting Support During Negotiations
Debt negotiations can be stressful even when they produce a workable outcome.
Useful support may include:
- Free debt advice to compare options and check offers.
- Help from a trusted representative if communicating with creditors is difficult.
Do not judge a settlement only by whether it promises emotional relief. Check the practical and legal terms as well.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Impact on different types of debt
Priority debts have more serious potential consequences, such as losing your home or essential services. Assess them before offering lump sums on ordinary unsecured debts.
As such, you may find that a priority creditor is less likely to accept a full and final settlement offer.
Priority debts include:
- Mortgage or rent arrears, particularly where your home is at risk.
- Council tax arrears
- Utility arrears where the supplier is threatening to disconnect you or install a prepayment meter
If you’re unsure what to do, I suggest you contact one of the UK’s leading charities that provide free debt advice.
My Creditors Refused to Settle Debt, What Should I Do?
While getting your offer refused can definitely be discouraging, you still have the lump sum of money.
Ask a debt adviser to compare alternatives before committing the remaining money. A rejected settlement does not automatically make an IVA the right next step.
An IVA’s term, contributions, fees and treatment of assets depend on its approved proposal.
A lump-sum IVA may be possible, but requires an insolvency practitioner, creditor approval and consideration of costs and consequences.
An IVA normally appears on a credit file for at least six years from approval and may remain longer if it is still ongoing.
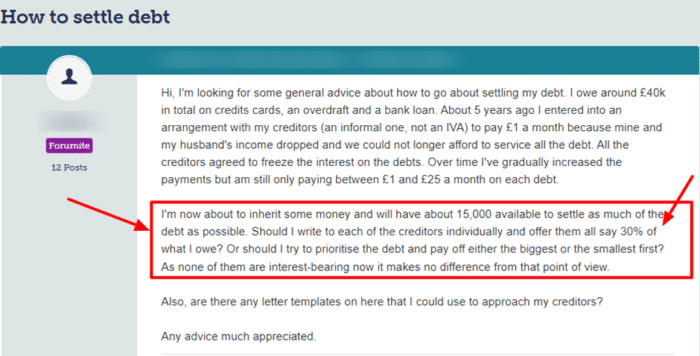
See the question one person asked on a popular forum about paying off debts.
Source: Moneysavingexpert
What is a Debt Management Plan (DMP)?
A DMP may suit someone with enough regular income to make sustainable payments; receiving a lump sum alone does not establish suitability.
Free debt advice is available from StepChange and National Debtline. PayPlan also offers free debt advice but is not a charity.
They’ll assess your financial information and give you advice on how much you should be paying as part of your debt management plan each month.
A DRO may be relevant if you meet its limits, but a lump sum or recent preferential payments can affect eligibility. Get advice before spending or distributing it.
In England and Wales, key limits include:
- Qualifying debts of no more than £50,000.
- Countable assets of no more than £2,000 and a qualifying vehicle worth no more than £4,000, with applicable exclusions and other conditions.
- Surplus monthly income of no more than £75. You must also meet residence and other eligibility requirements and cannot own your home.
If you feel you are eligible for a DRO, you should contact a DRO adviser.
An approved intermediary checks eligibility and submits the application. You cannot apply directly without that process.
There is no DRO application fee in England and Wales. Northern Ireland has separate rules, so check the right jurisdiction.
Misconceptions about debt
Many people in debt are scared to deal with their debt because of stories they’ve heard.
Some common concerns need a more precise explanation:
- When I miss a payment on a debt, I will be blacklisted. A blacklist does not exist
- Ordinary inability to repay consumer credit is not itself a criminal offence. Criminal fines and some public debts have distinct enforcement rules; obtain advice about those cases.
- Energy arrears can lead to enforcement or changes to payment arrangements under the applicable safeguards. Contact the supplier promptly; do not rely on an absolute promise that supply cannot be affected.
- I’ll be liable for someone else’s debt who lived at my address before I did. Not true
- Moving abroad does not automatically cancel a debt or prevent lawful recovery.
Understanding the Legal Aspects of Debt Settlement
It’s important that you understand the legal aspects of debt settlement. I suggest you discuss your situation with a debt expert at one of the UK’s leading charities.
Charities provide free debt advice and could help you decide how to make a debt settlement offer.
That said, some debt situations require more than ‘advice’. In this instance, a solicitor could be of assistance.
This can be especially true if you need legal representation in a complex court case.
Costs and Tax Questions
Check the costs and any wider consequences before agreeing a settlement.
Questions to resolve include:
- How the account will be reported to credit reference agencies.
- Whether interest, court costs or other permitted charges are included in the agreed figure.
- Whether an adviser or intermediary is charging you a fee.
- Whether your particular business or tax circumstances require professional tax advice.
A personal consumer-debt settlement should not be explained using a blanket rule for company taxation.
For companies, releases of debt can engage specialist loan-relationship and insolvency rules, with exceptions. A forgiven balance is not automatically taxable in every case.
Get advice from an accountant about any business-debt settlement or possible relief.
There is no universal 20% tax charge on a forgiven debt. The applicable treatment depends on the taxpayer and transaction.
Negotiation Tips for Debt Settlement
Negotiating with creditors can be stressful especially if you’re struggling with your finances.
In England and Wales, ask an eligible debt adviser whether the statutory Breathing Space scheme is suitable. You cannot start it simply by asking a creditor for a 60-day pause.
A standard Breathing Space generally lasts up to 60 days and restricts most enforcement, contact, interest and charges on qualifying debts. It is not a write-off or general payment holiday; ongoing liabilities and scheme conditions still apply.
That said, you should:
- Make sure all creditors provide their acceptance of a full and final settlement offer in writing. Keep copies in case you need them should a dispute arise which could be years later
- Do NOT send a lump-sum payment before creditors accept your offers
- A payment made by a third party can have different legal consequences from paying your own money. It does not remove the need for clear written acceptance; get advice if the agreement or source of funds is complicated.
- If the debt is significant, you may want a solicitor to draw up an agreement which creditors and you sign
- Always keep copies of letters and other correspondence
Staying On Top Of Your Debts
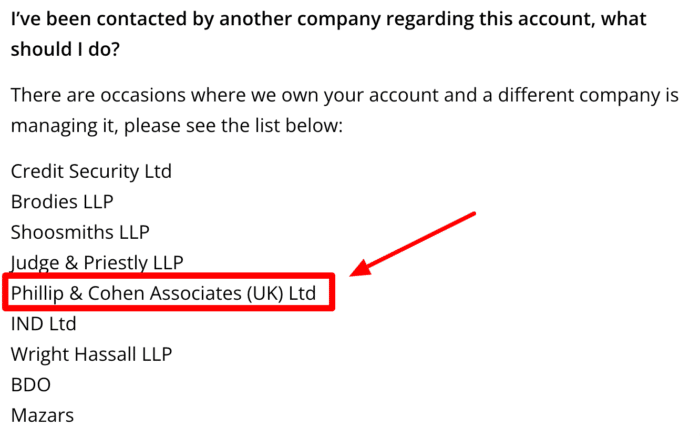
A letter may come from the original creditor, a debt purchaser or a separate collection agency. Check the business name and contact details against reliable records, and ask it to explain who owns the debt and its authority to collect. Keep earlier correspondence so you can trace any change of owner or representative.
- Robinson Way will sometimes contact you under the name Hoist Finance.
- Cabot Financial Group recently bought Wescot Credit Services
- Credit Style communicate as both Credit Style and CST Law.
- Lowell Financial also owns Overdales and collects debts under both names.
References




