


CCJ Sent to an Old Address: How to Apply to Set It Aside


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you worried about a CCJ sent to your old address? Are you scared about a bailiff knocking on your door or taking your things?
Check the judgment and claim details promptly. The court can explain how to obtain copies, and an adviser can assess possible grounds for a set-aside.
This article will help you understand and deal with this tough situation. We’ll cover:
- What a CCJ is and how to find out where it was issued.
- How to get a copy of your credit record.
- What steps you should take if you come across a CCJ.
- How to seek legal advice and possibly write off some debt.
- What happens if the claimant was not told about your new address.
Citizens Advice estimate households have around £18.9 billion in unpaid bills like council tax and utilities1. So, being concerned about debt and its implications is common.
In fact, some of us here at MoneyNerd have faced debt collectors too. We know how it feels, and we’re here to help you.
Let’s dive into learning more about managing a CCJ sent to an old address and protecting your credit file.
What is a CCJ?
A County Court Judgement (CCJ) is an order from a judge that states you have to pay the debt. This means that the court agrees with your creditor, and you owe the money.
Your judgement will include the following:
- How much you owe
- How you should pay
- Who you should pay
- Your deadline to pay.
Unless you pay within one month of the CCJ being issued, it will be recorded in the Register of Judgements, Orders and Fines for 6 years. If you pay off your debt within these 6 years, you can request that your judgement is marked as ‘satisfied’ on the register.
To do this, write to the court with proof that you have paid off the debt in full.
Full payment within one calendar month of judgment allows you to seek removal from the register. Send proof to the court; do not assume that payment automatically prevents registration.
A CCJ normally appears on your credit file for six years from the judgment date unless it is removed earlier under the applicable rules. It can make borrowing harder or more expensive, but it does not make all credit impossible.
Lenders consider a CCJ when assessing credit risk. A default judgment can arise without a defended hearing, so its existence does not prove that you knew about the claim or deliberately refused to pay.
Understandably, companies are going to be reluctant to give you credit!
After 6 years, it is no longer visible on your credit report and you should find it easier to get credit again.
What happens if the claimant wasn’t told your new address?
Your Rights With Bailiffs
It’s crucial to understand your rights when dealing with bailiffs. That’s why I’ve put together this table that explains what bailiffs can and can’t do. For more information, don’t forget to read our detailed guide.
| Bailiffs may | Important limits |
|---|---|
| Visit under a valid enforcement power | Normally at least 14 clear days’ notice is required before taking control of goods; courts can shorten notice. An eligible debt-advice request can extend it to 28 clear days. |
| Take non-exempt goods belonging to the debtor | They cannot take ordinary essential household items or someone else’s property. Some jointly owned goods may be affected. |
| Take a vehicle where legally permitted | Ownership, finance, disability and other exemptions must be checked. ANPR does not remove those limits. |
| Enter through a door when lawful | For ordinary civil debts they usually cannot force first entry to a home. A CCJ by itself is not a power to break in. |
| Enter into a controlled goods agreement | Ask for a clear inventory and terms; breaking an agreement can have serious consequences. |
| Sell goods under the enforcement rules | Notice and sale requirements apply. Get advice if you dispute ownership, exemption, entry or fees. |
England and Wales only. Tools and equipment needed personally for work, study or education have a combined exemption limit of £1,350. The rules differ elsewhere in the UK.
How do you check if you’ve got a CCJ?
What if I ignore a CCJ?
Ignoring a CCJ, even if you think there’s been a mistake, is not a good idea.
Ignoring a CCJ can allow the creditor to seek enforcement. If you dispute it, obtain the claim and judgment from the court and seek advice promptly about an N244 application, evidence and any request to stay enforcement.
A creditor may apply for an appropriate warrant or writ of control. Enforcement agents can add lawful fees. For taking-control-of-goods action under the rules effective from 1 May 2026, notice is normally at least 14 clear days, or 28 clear days if a qualifying debt-advice request is made before that period expires. Exceptions and transitional rules apply.
Our financial expert, Janine Marsh, advises: ‘If a bailiff has proven you owe money and you don’t have cash to hand, you’re within your rights to suggest a payment plan. It’s not a guarantee, but many will accept this as it’s easier than repossession.
With the required authority, enforcement agents may take control of eligible goods belonging to you. Essential and other exempt goods are protected, and payment or challenge options depend on the circumstances.
For an ordinary civil money debt, bailiffs normally cannot force first entry into a home. Lawful re-entry to remove controlled goods after a broken agreement has separate conditions; a non-exempt vehicle outside may still be at risk.
Other enforcement options may include an attachment of earnings order, charging order or third-party debt order. A creditor’s bankruptcy petition normally requires at least £5,000 and further legal steps; bankruptcy does not happen automatically.
The court may order you to attend to provide financial information. Failure to comply can lead to contempt proceedings and, in some cases, imprisonment. Ordinary inability to pay a CCJ is not itself a reason for imprisonment.
» TAKE ACTION NOW: Fill out the short debt form
What should you do if the CCJ is valid?
Should you contact the Court?
Can a court find your file?
What are the chances of a CCJ being set aside?
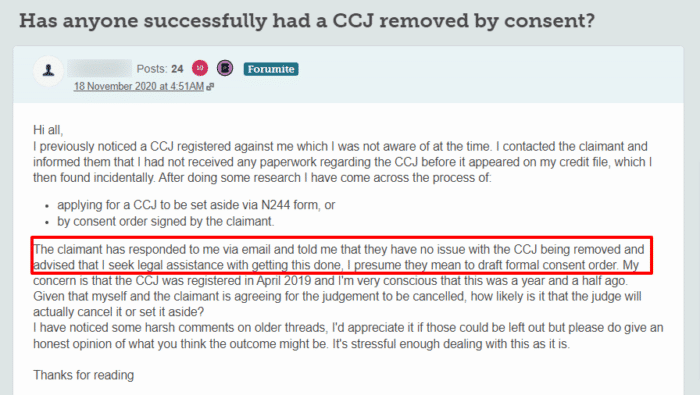
Can the claimant agree to setting aside a CCJ?
What happens when a CCJ is set aside?
How do you find where a CCJ was issued?
CCJ sent to the old address, what should you do? RECAP
Should you seek legal advice?
If you are concerned about the cost of getting legal advice, you do have options:
- Debt charities can give free debt advice and help identify the next step. Check whether they can assist with the particular court application; commercial referral services are not automatically charities or solicitors.
- Some solicitors offer an initial consultation without charge; confirm the scope and cost before booking.
- Law clinic: your local university may have a law clinic that will offer legal services.
- Legal aid is generally unavailable for ordinary debt disputes in England and Wales unless your home is at risk, with limited exceptional-case provisions. Check both the subject-matter and financial eligibility rules; do not assume a CCJ set-aside is funded.
References




